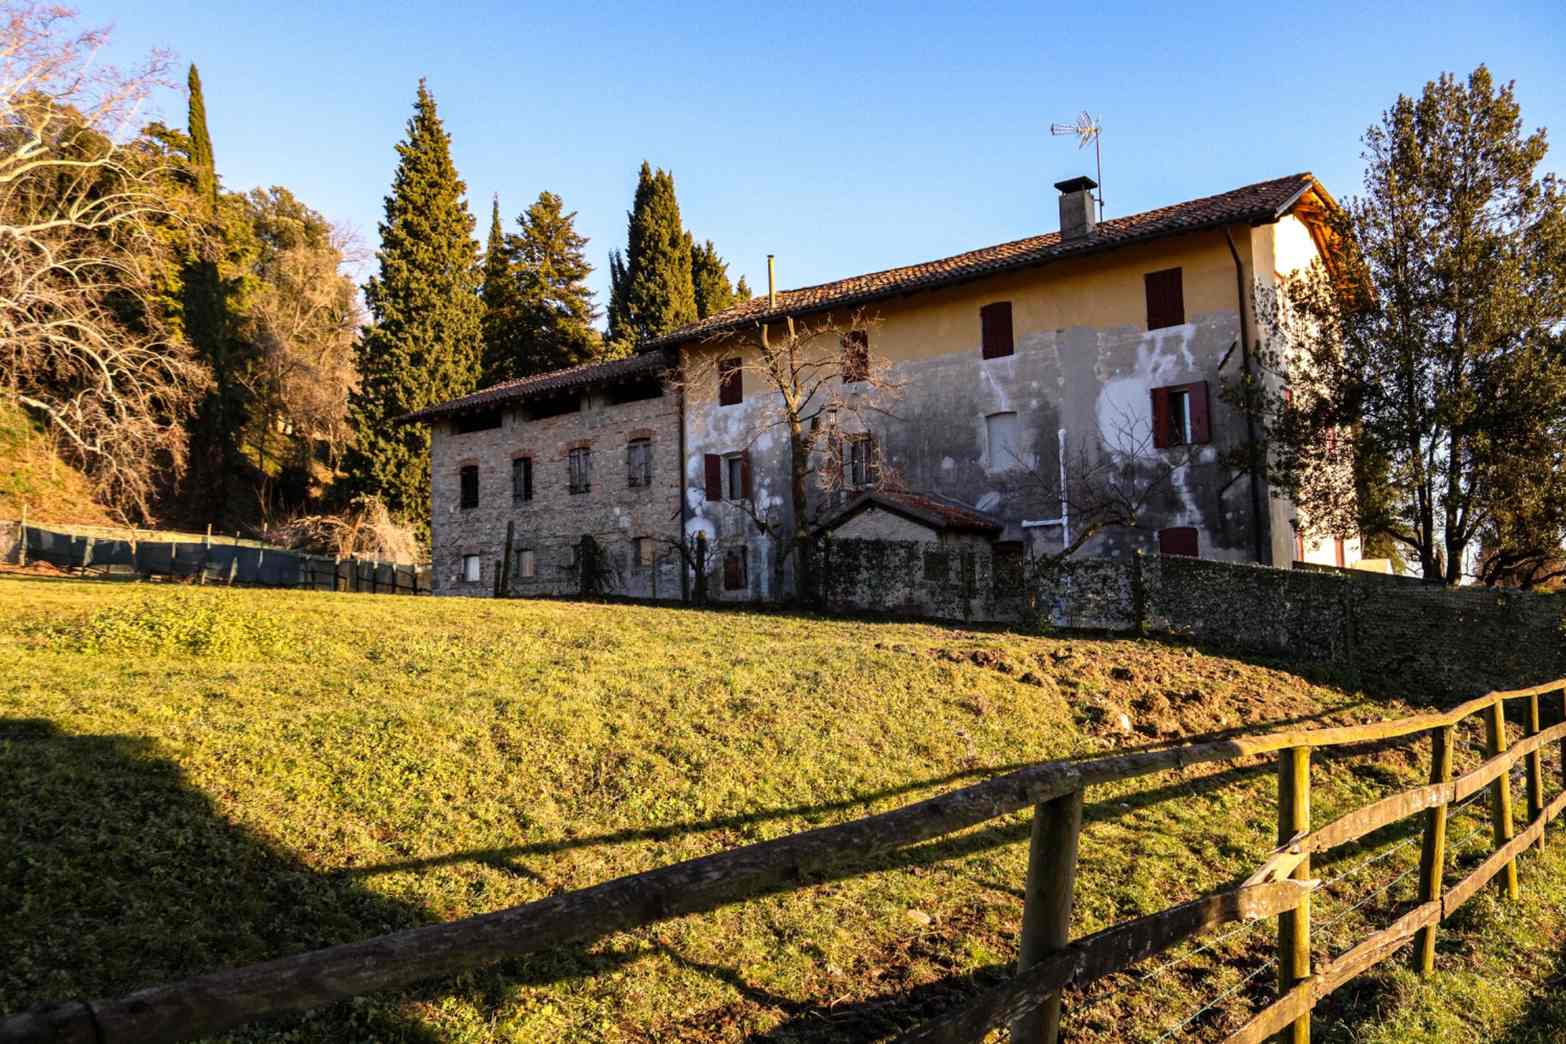
For many years, Italian agritourism was primarily viewed as an extension of farming: a limited number of rooms, family-led management, food and beverage closely linked to the estate’s own agricultural production, and a business model heavily dependent on the direct involvement of the owners.
That model continues to play an important role.
But it is no longer the only one.
A different category is emerging: professionally managed agritourism, structured as a genuine hospitality business, supported by management reporting, sophisticated pricing, professional distribution, clearly defined management responsibilities and the ability to generate measurable cash flows.
It is through this transformation that agritourism can begin to attract the attention of professional investors, family offices, club deals, hospitality operators and institutional capital.
The defining factor is not the number of rooms.
Nor is it the level of luxury.
It is the asset’s ability to become:
measurable, manageable, financeable, scalable and transferable.
When these conditions are met, agritourism ceases to be merely a real estate holding or a family-run business.
It becomes a hospitality investment.
From rural estate to investable hospitality asset
Many Italian agritourism businesses originate from pre-existing family assets:
-
farmhouses;
-
agricultural estates;
-
vineyards;
-
olive groves;
-
historic residences;
-
rural buildings;
-
land subsequently integrated into a hospitality operation.
The fundamental issue is that real estate value and economic value do not necessarily coincide.
A property may offer exceptional architectural, landscape or locational qualities while still generating inadequate returns on the capital invested.
A professional assessment of an agritourism asset should therefore move beyond the question:
What is the property worth?
The more relevant questions are:
How much capital does it absorb, how much cash flow can it generate, and what return can it produce over time?
This is the same principle underpinning the analysis of hotel investments on InvestimentiAlberghieri.it: real estate value is only one component of the investment case.
The other is the asset’s ability to generate sustainable income.
The seven criteria for institutional readiness
There is no automatic threshold at which an agritourism property becomes “institutional”.
There are, however, a number of factors that indicate whether an asset is evolving towards the standards expected by professional investors.
1. Transparent governance
Investors must be able to clearly distinguish between:
-
real estate ownership;
-
operating management;
-
agricultural activities;
-
hospitality;
-
food and beverage;
-
events;
-
ancillary business lines.
When all activities sit within the same entity without clear financial attribution, it becomes difficult to identify where margins are actually generated.
Professionalisation therefore begins with economic and corporate transparency.
2. Normalised EBITDA
Revenue alone is not enough.
The sustainable operating performance of the business must be identified.
This requires a proper breakdown of:
-
rooms revenue;
-
food and beverage revenue;
-
events revenue;
-
wellness revenue;
-
experiential revenue;
-
agricultural revenue;
-
payroll costs;
-
OTA commissions;
-
maintenance;
-
utilities;
-
distribution costs;
-
marketing;
-
general and administrative expenses.
Only after this exercise can the investor determine what portion of profitability is truly sustainable.
For a professional investor, the key question is not how much revenue the property generates.
It is how much sustainable EBITDA the business can produce.
3. Management independence from ownership
An asset is not truly investable if its entire operation depends on one individual.
If bookings, staffing, suppliers, sales, pricing and guest relationships all ultimately depend on the owner, operational risk remains high.
A professional agritourism business should therefore progressively establish:
-
procedures;
-
clearly defined roles;
-
delegated responsibilities;
-
management reporting;
-
KPIs;
-
budgets;
-
forecasts;
-
operating standards.
The objective is to move from an owner-dependent business to a management-driven organisation.
4. Structured revenue management
Pricing can no longer be determined simply by dividing the year into high and low season.
A professional asset should adopt hotel-style revenue management disciplines, including:
-
dynamic ADR management;
-
pickup analysis;
-
booking-window analysis;
-
minimum-stay controls;
-
market segmentation;
-
event pricing;
-
cancellation management;
-
direct-booking strategies;
-
RevPAR analysis;
-
optimisation of total revenue per guest.
A professionally managed property is not simply trying to maximise occupancy.
It is looking for the optimum balance between occupancy, ADR, RevPAR and profitability.
5. Planned CAPEX
Rural real estate can carry substantial maintenance and investment requirements.
Roofs, mechanical systems, swimming pools, water networks, land, kitchens, internal roads, HVAC systems and historic buildings can all generate significant capital expenditure.
A professional asset therefore needs a multi-year CAPEX plan.
It is not enough to understand how much has already been invested.
Investors need visibility on how much capital will be required over the next:
-
three years;
-
five years;
-
ten years.
A clear distinction should also be made between:
maintenance CAPEX and growth CAPEX.
The former protects the asset’s competitiveness.
The latter should create incremental value.
6. Diversified distribution
An agritourism business heavily dependent on OTAs may still achieve strong occupancy, but its commercial model can remain vulnerable.
A more sophisticated operator should progressively build a balanced distribution mix across:
-
OTAs;
-
direct website;
-
CRM;
-
proprietary customer database;
-
direct campaigns;
-
newsletters;
-
SEO;
-
social channels;
-
specialist operators;
-
luxury travel advisors;
-
destination partnerships.
Direct business is not merely a distribution metric.
It is also an indicator of brand strength and ownership of the customer relationship.
The broader issue of positioning and distribution independence is also explored on RobertoNecci.it.
7. Exit visibility
Professional capital is more likely to enter an investment when there is a credible route to exit.
Investors should therefore ask:
-
Who could acquire the asset in five or seven years?
-
Another family office?
-
A hospitality operator?
-
A fund?
-
A multi-property platform?
-
A real estate investor?
Exit strategy is not something to consider only when the asset is placed on the market.
It should be part of the investment thesis from day one.
Luxury does not make an asset institutional
One of the most common mistakes is to confuse premium positioning with institutional investability.
A swimming pool, spa, designer rooms, fine dining and a prestigious location can all enhance the commercial appeal of a property.
But they do not automatically turn it into an institutional-grade investment.
An agritourism business can be visually exceptional while still being:
-
poorly profitable;
-
overleveraged;
-
excessively dependent on its owner;
-
undercapitalised;
-
highly seasonal;
-
lacking proper reporting;
-
unable to fund its own CAPEX requirements.
True institutionalisation occurs when a high-quality product is combined with managerial and financial discipline.
A numerical example
Consider a premium rural hospitality property with:
-
30 rooms;
-
average ADR of €310;
-
average annual occupancy of 64%;
-
rooms revenue of approximately €2.17 million;
-
F&B, events and experiential revenue of €1.05 million;
-
total revenue of approximately €3.22 million.
At a GOP margin of 34%, GOP would be approximately:
€1.09 million.
After general expenses, management fees and other operating costs, assume normalised EBITDA of:
€850,000.
At this point, the investment analysis changes completely.
The question is no longer simply:
What is the farmhouse worth?
The investor begins to assess:
-
underlying real estate value;
-
normalised EBITDA;
-
implied valuation multiple;
-
debt capacity;
-
DSCR;
-
future CAPEX requirements;
-
equity returns;
-
exit assumptions.
This is the conceptual shift that separates a hospitality asset from a simple accommodation property.
Seasonality as a financial risk
Seasonality is often treated as an unavoidable feature of rural tourism.
From a financial perspective, however, it represents risk.
A property generating most of its annual revenue within four months may show attractive headline profitability while maintaining a highly vulnerable cash-flow profile.
Professionalisation therefore requires a structured approach to extending the operating season through complementary demand segments such as:
-
international leisure;
-
wine tourism;
-
wellness;
-
weddings;
-
corporate retreats;
-
events;
-
cycling tourism;
-
gastronomic tourism;
-
curated experiences;
-
themed stays.
The objective is not to eliminate seasonality.
It is to reduce the concentration of risk.
Agriculture: direct and indirect profitability
Agricultural operations should not be assessed exclusively on the basis of their standalone margin.
In many cases, their greatest economic value is transferred indirectly to the hospitality product.
Vineyards, olive groves, vegetable gardens and estate-produced food can support:
-
storytelling;
-
authenticity;
-
food and beverage;
-
experiences;
-
brand positioning;
-
premium pricing.
A vineyard may therefore produce relatively modest agricultural returns while simultaneously supporting a significantly higher hospitality ADR.
A professional investment analysis should capture both dimensions.
PropCo and OpCo structures
For more sophisticated assets, separating the real estate component from the operating business may create greater financial clarity.
PropCo
Owns:
-
real estate;
-
land;
-
infrastructure;
-
key physical assets.
OpCo
Operates:
-
accommodation;
-
food and beverage;
-
events;
-
wellness;
-
experiences;
-
sales and marketing;
-
employees.
This structure allows investors to distinguish between two different return profiles:
real estate returns and operating returns.
PropCo/OpCo structures are already widely used in conventional hospitality and could increasingly become relevant within professional rural hospitality.
On InvestHotel.it, the relationship between capital structure, operating cash flow, debt sustainability and asset value is a central component of hotel investment analysis.
The bankability of agritourism
Underlying real estate value should not be the only factor used to determine debt capacity.
Lenders should assess:
-
EBITDA;
-
free cash flow;
-
DSCR;
-
LTV;
-
seasonality;
-
CAPEX;
-
break-even;
-
debt service;
-
base-case assumptions;
-
downside scenarios;
-
stress tests.
An agritourism asset may be strongly backed by real estate yet remain financially fragile.
Conversely, a less asset-heavy business may possess exceptional cash-generating capacity.
Sound financing requires an understanding of both dimensions.
The role of luxury rural hospitality
International guests choosing premium agritourism are not simply purchasing a room.
They are buying:
-
privacy;
-
nature;
-
gastronomy;
-
identity;
-
destination;
-
wellness;
-
design;
-
authenticity;
-
experience.
This positioning enables certain rural properties to achieve pricing levels comparable with upscale and luxury hotels.
However, premium positioning must be supported by a coherent economic model.
Luxury without profitability is not an investment strategy.
It is simply an expensive product to maintain.
The question of scale
Not every agritourism business can become an institutional investment.
Scale still matters.
A very small property may struggle to support, on a standalone basis:
-
management;
-
revenue management;
-
sales;
-
marketing;
-
management control;
-
technology;
-
corporate infrastructure.
But scale does not necessarily require turning every property into a large resort.
It can also be created through:
-
aggregation;
-
management companies;
-
multi-property platforms;
-
shared brands;
-
regional acquisitions;
-
centralised services.
This may represent one of the most interesting long-term opportunities within the sector.
Italy has thousands of high-quality rural properties, but the market remains highly fragmented.
Bringing distinctive assets together under a common management platform could create a new category of hospitality investment.
From family asset to family office
Many agritourism businesses are owned by families whose wealth may simultaneously include:
-
real estate;
-
agricultural land;
-
farming businesses;
-
hospitality assets;
-
corporate shareholdings.
As the asset base expands, the challenge is no longer purely operational.
It becomes a governance issue.
Generational transition may therefore provide an opportunity to transform a family-owned property into a more structured investment vehicle.
At this stage, potential capital providers or partners may include:
-
family offices;
-
club deals;
-
private investors;
-
industrial partners;
-
hospitality operators;
-
real estate investors.
This transition should be supported by independent analysis and a clear distinction between real estate value, operating value and development potential.
The integrated assessment of operations, strategy, organisational structure and financial sustainability also underpins the work carried out by HotelManagementGroup.it.
The real test: the investment committee
One of the simplest ways to determine whether an agritourism property is evolving into a professional investment asset is to imagine presenting it to an investment committee.
The questions would be immediate:
What is the normalised EBITDA?
What CAPEX is required?
How concentrated is demand?
How dependent is the property on OTAs?
What is the customer acquisition cost?
What is the DSCR?
What is the underlying real estate worth?
What is the operating business worth?
What downside scenario has been modelled?
Who will manage the asset without the owner?
What is the exit strategy?
When the owner or operator can answer these questions with verifiable data, the investment profile of the property changes fundamentally.
Can agritourism become a new asset class?
Probably not as a fully homogeneous category.
The sector remains too fragmented, with significant differences between individual properties and business models.
However, a segment is clearly emerging with characteristics increasingly comparable to professional hospitality:
-
hard-to-replicate locations;
-
strong international demand;
-
high ADR potential;
-
experiential positioning;
-
high-quality real estate;
-
development potential;
-
barriers to entry;
-
structurable cash flows.
When these characteristics are combined with professional governance, management and financial discipline, the nature of the investment changes.
Agritourism ceases to be merely a rural property offering guest rooms.
It becomes a hospitality investment platform.
Conclusion
The future of professional agritourism will not necessarily depend on building ever larger properties.
It will depend on building better businesses.
An asset becomes genuinely attractive to professional capital when investors can clearly measure:
revenue, margins, EBITDA, CAPEX, debt, cash flow, risk and returns.
The key point is straightforward:
an agritourism property does not become institutional because it is luxurious.
It becomes institutional when it is:
measurable, financeable, manageable, scalable and transferable.
That is the point at which rural real estate fully enters the language of professional hospitality investment.
CTA
Are you evaluating the acquisition, repositioning or value enhancement of an agritourism property, rural resort or hospitality-related rural estate?
Investimenti Alberghieri provides strategic, operational and financial analysis for owners, investors, family offices, financial institutions and hospitality operators.
Contact: info@investimentialberghieri.it
Further insights:
InvestimentiAlberghieri.it
InvestHotel.it
RobertoNecci.it
HotelManagementGroup.it