Twenty units.
Forty beds.
Almost five hectares of land.
A restaurant.
A natural swimming pool.
A five-star project in the heart of the upper Val di Non.
And an investment of up to approximately:
€10 million.
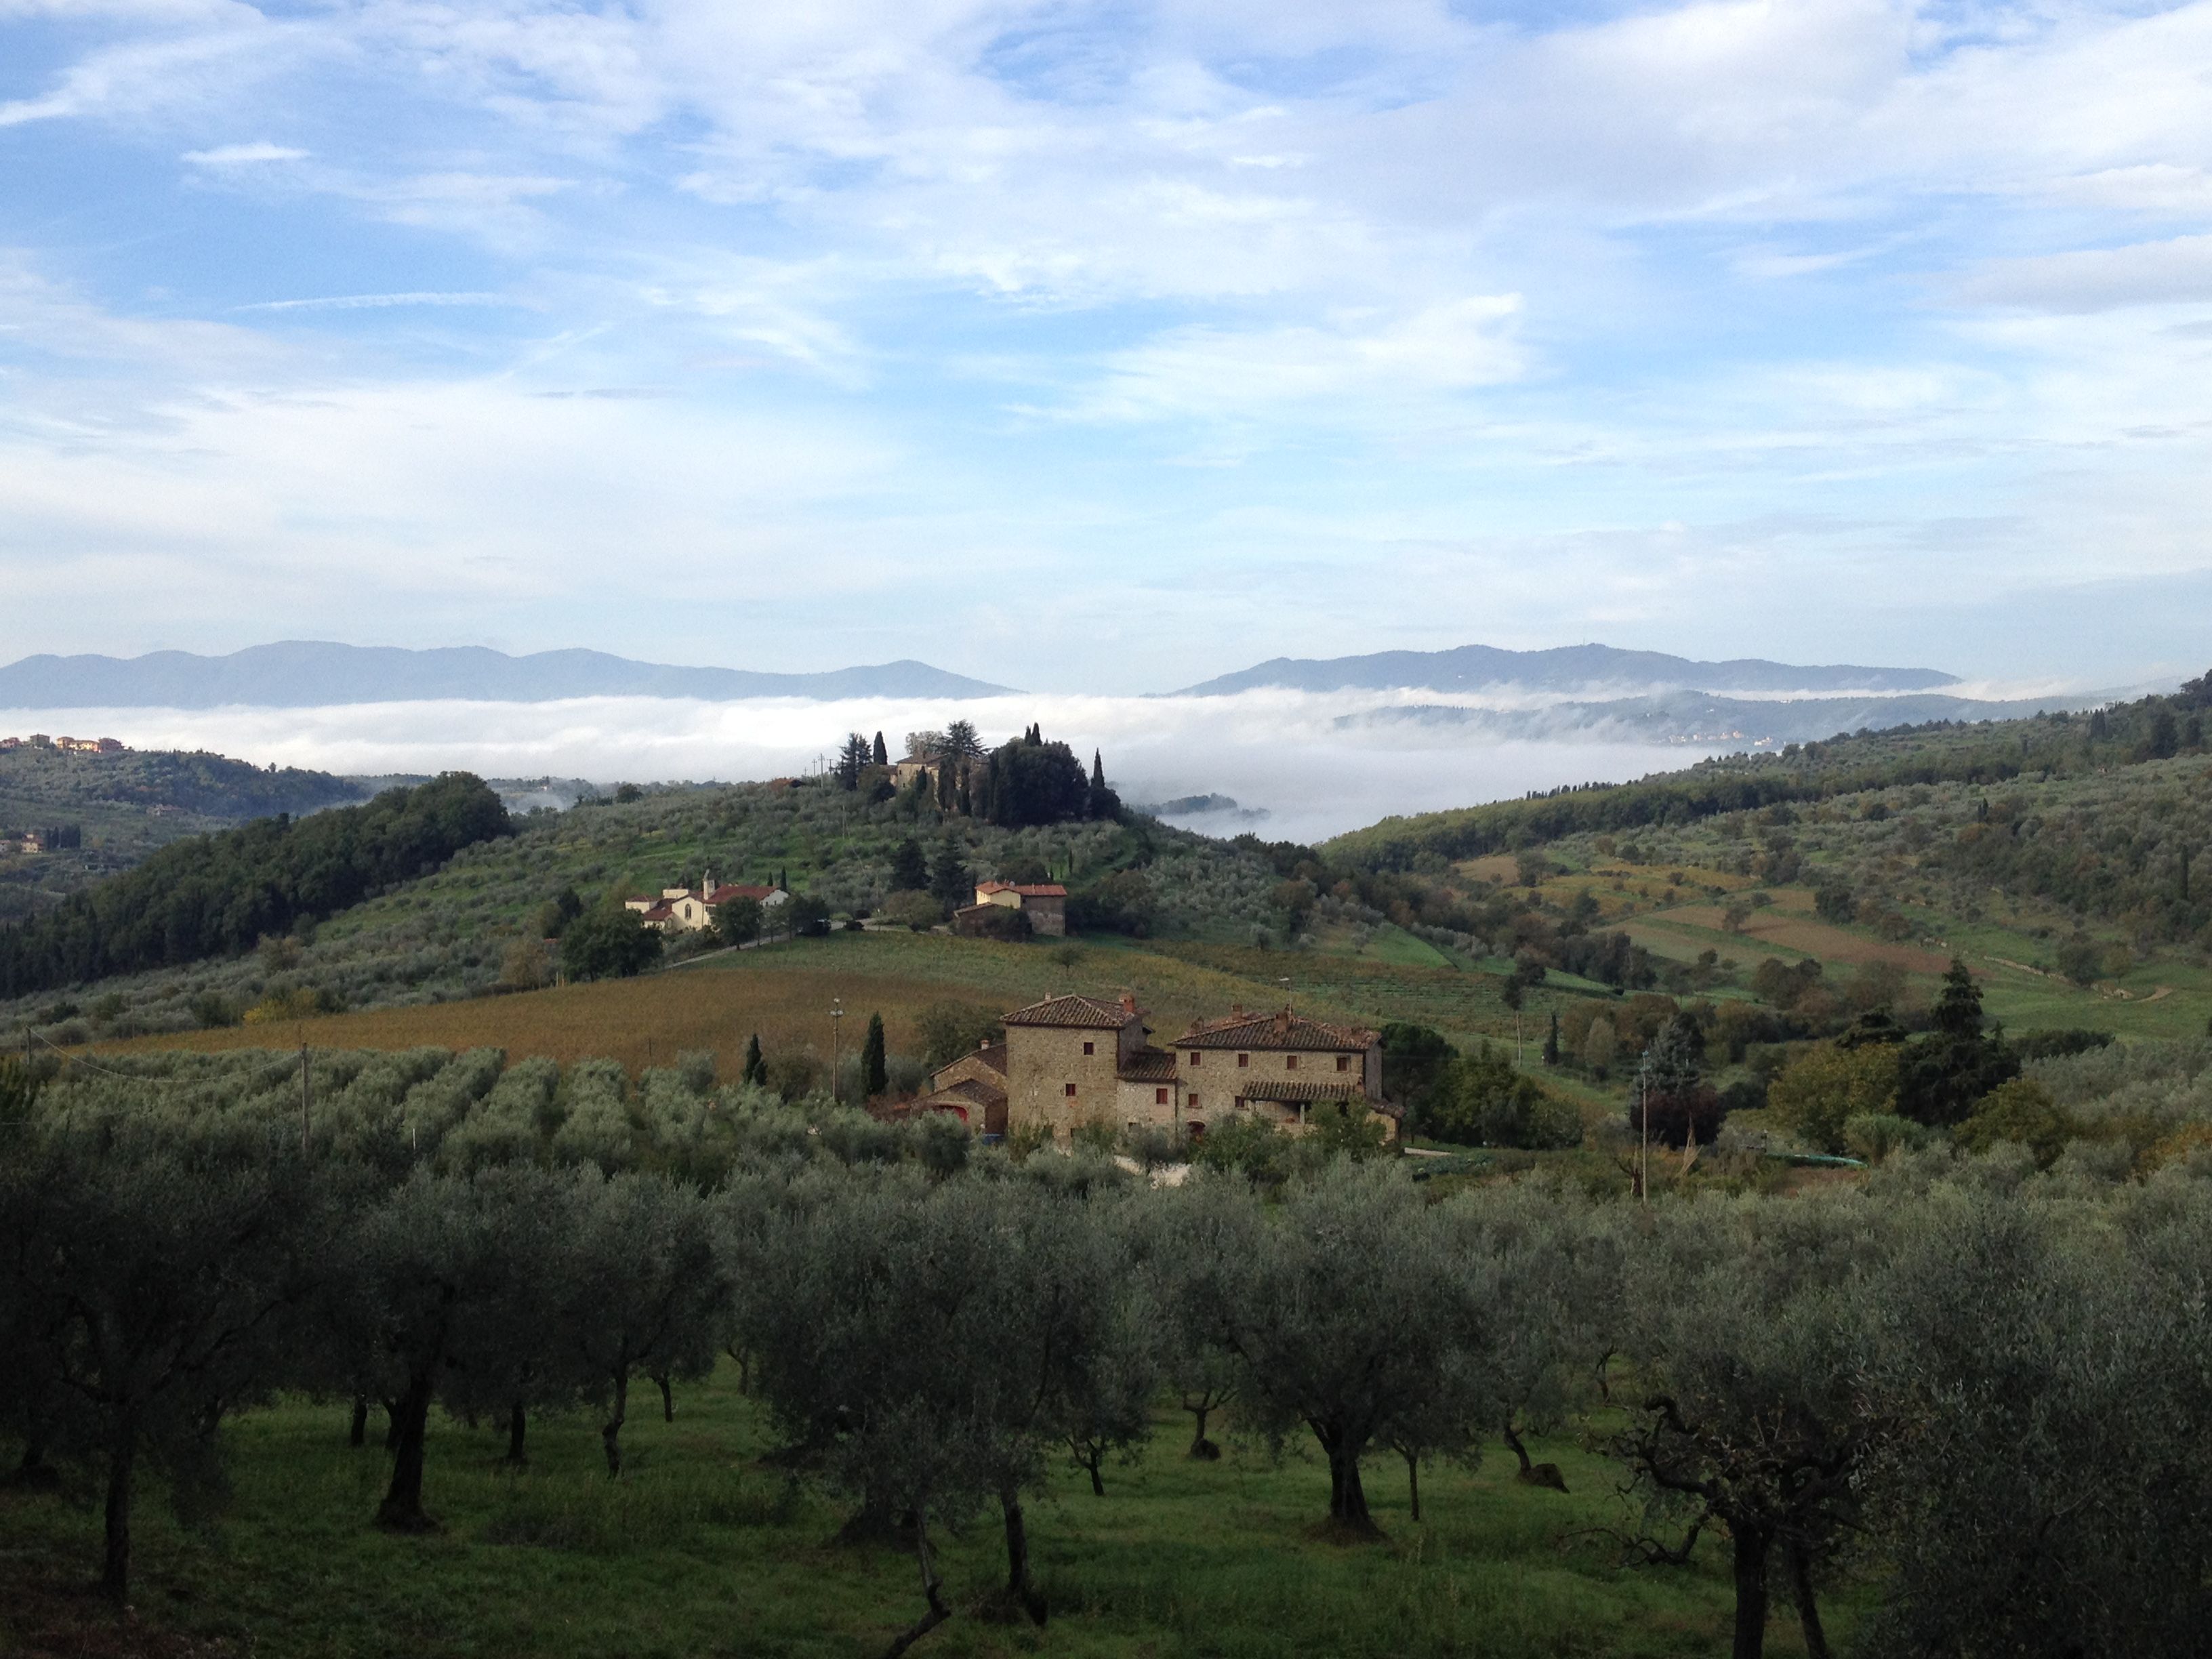
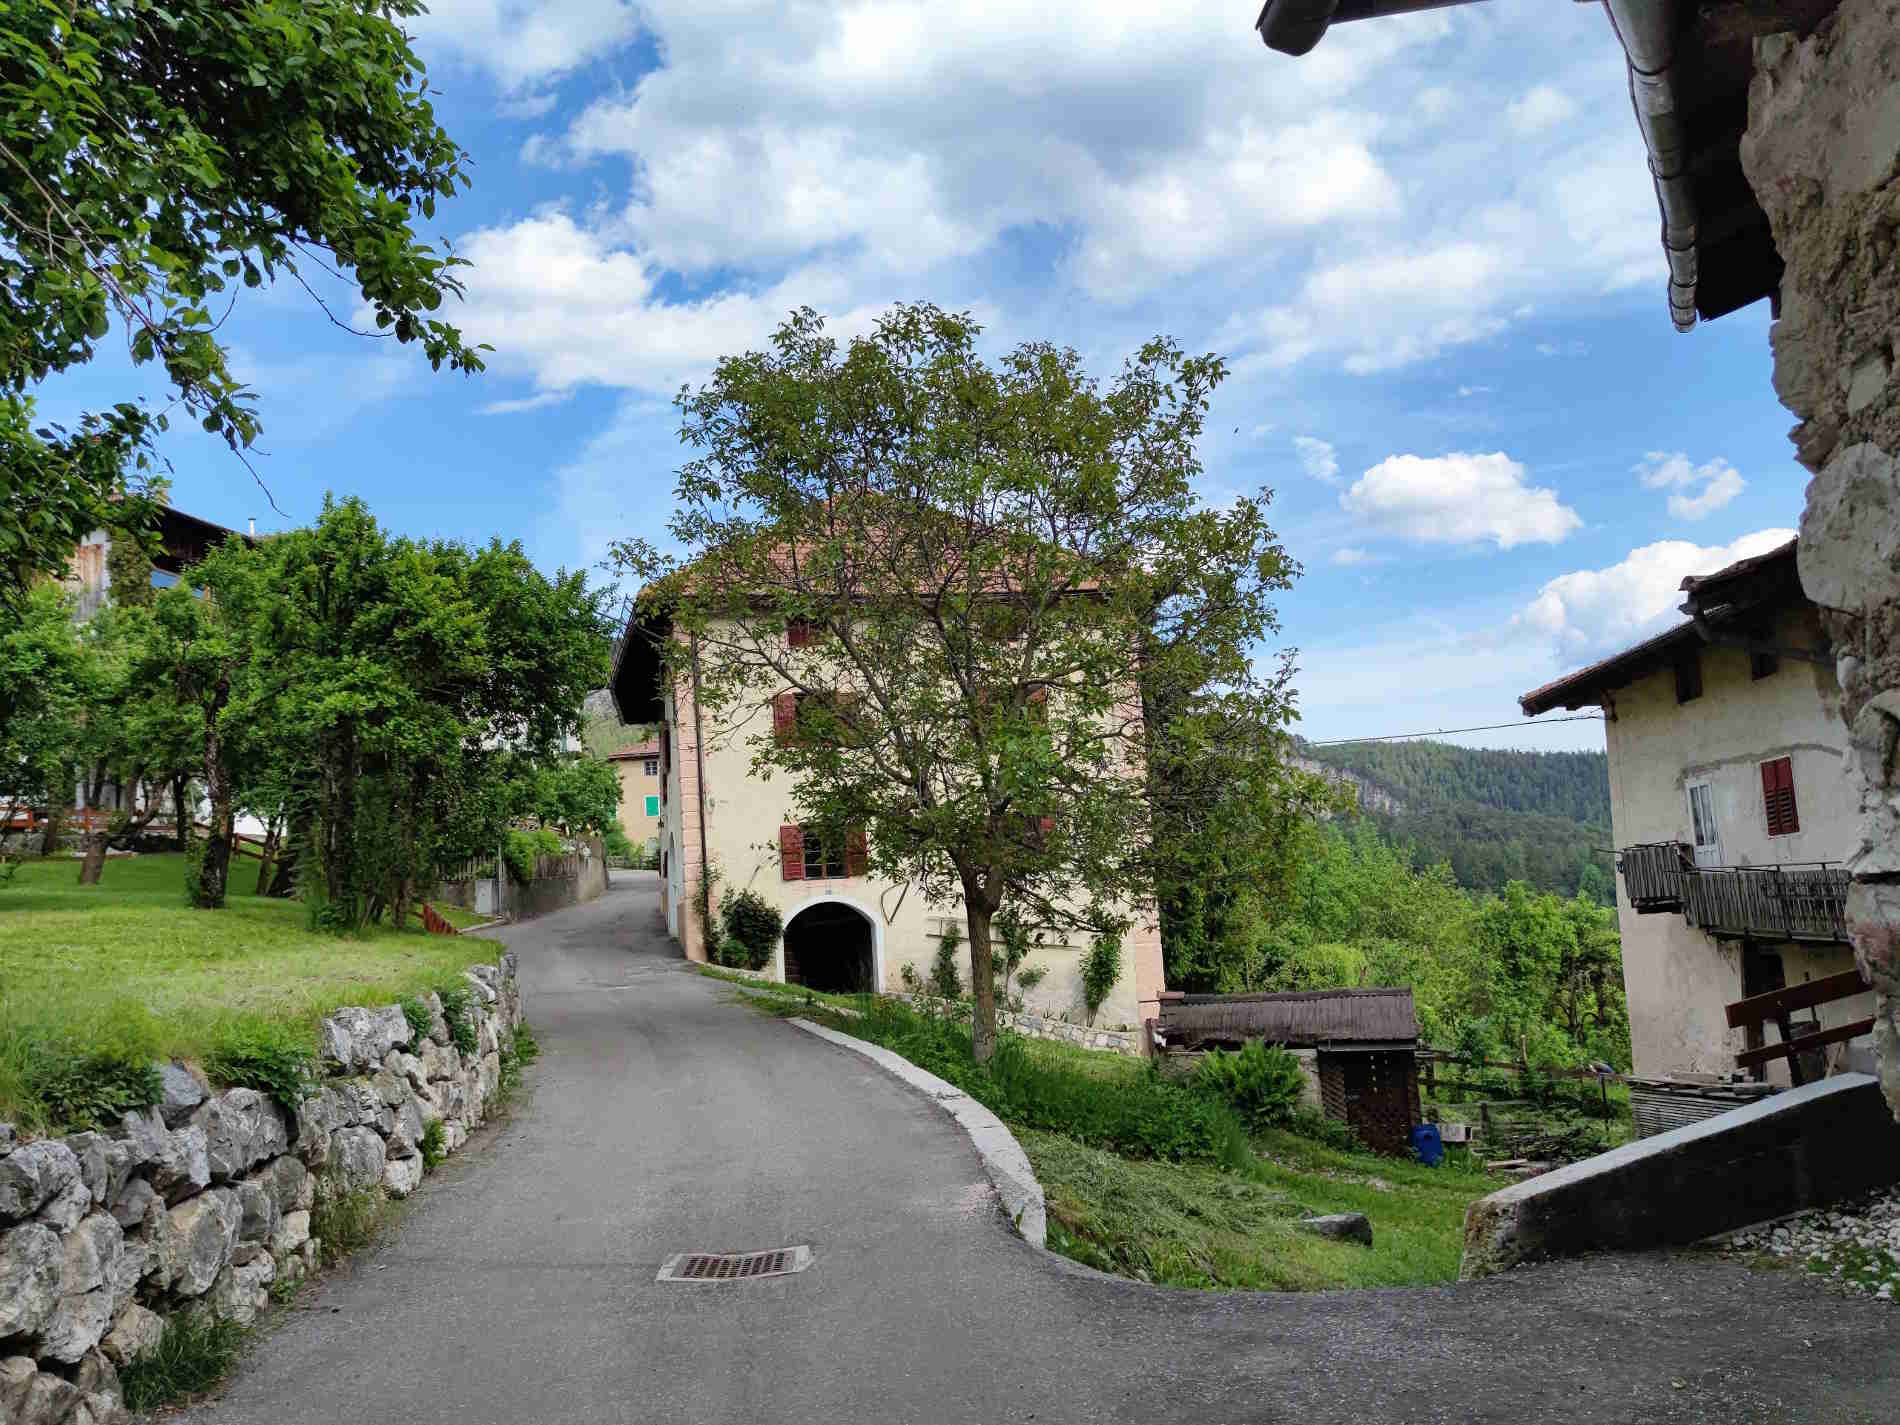
In Tret, a village within the municipality of Borgo d’Anaunia, HBW Tourism Development Srl plans to restore and extend Maso Fandoveri, transforming it into a high-end hospitality property.
The project includes 20 two-person accommodation units, providing capacity for 40 guests, together with a restaurant, spaces dedicated to the food and wine experience, a natural swimming pool and the productive restoration of almost five hectares of land.
The architectural design has been entrusted to Bergmeisterwolf.
The Borgo d’Anaunia Municipal Council unanimously approved the planning derogation required for the development. The authorisation process, however, cannot yet be considered fully completed, as a further provincial-level approval stage is still required.
On 4 August 2026, the municipality had already published notice of the building permit application for the:
“development, by way of planning derogation, of a new hotel operation through change of use and extension of Maso Tret–Fandoveri.”
The project is therefore tangible.
But from the perspective of InvestimentiAlberghieri.it, the most interesting question is not:
“Will this be a beautiful hotel?”
It is:
“What level of economic performance must 20 units generate to remunerate an investment of up to €10 million?”
The First Number: Approximately €500,000 per Unit
Based solely on the figures currently available:
Indicative Investment
€10,000,000
Units
20
the result is:
approximately €500,000 per unit.
This is a purely theoretical ratio.
We do not yet know in detail:
-
the effective land or acquisition cost;
-
the equity structure;
-
debt financing;
-
potential grants or incentives;
-
financing costs;
-
working capital;
-
contingency;
-
the final CAPEX breakdown.
But the figure is already sufficient to classify the project as:
High Capital Intensity.
And from that point onwards, the economics of the business plan change materially.
High Capital per Key Requires High Productivity per Key
The relationship is straightforward:
Higher Capital per Key
↓
Higher Required ADR
↓
Higher Required GOPPAR
↓
Higher Required EBITDA
↓
Higher Required Stabilised Value.
The more capital concentrated in each room, the greater the income each room must generate.
The issue is therefore not spending a large amount of capital.
The issue is:
making the asset on which that capital is spent productive enough to justify it.
Rural Luxury Is Not Automatically Profitable Luxury
Maso Fandoveri incorporates many features consistent with a high-end positioning:
-
natural setting;
-
distinctive architecture;
-
low density;
-
landscape;
-
gastronomy;
-
agriculture;
-
sustainability;
-
privacy;
-
experience.
But none of these factors automatically generates an adequate return.
The real question is:
how much is the guest willing to pay for that specific experience?
Luxury hospitality is not ultimately measured by stars.
It is measured by:
Pricing Power.
Year-Round Opening Makes the Equation More Interesting
One of the most relevant elements of the project is the intention to operate:
twelve months a year.
With 20 units, theoretical annual inventory amounts to:
20 × 365
=
7,300 available room nights.
From that point onwards, the value of the project depends on its ability to convert that inventory into paying demand.
Three Rooms Revenue Scenarios
The following scenarios are purely illustrative.
They are not forecasts for the project.
Scenario 1 — Conservative
Occupancy:
50%
ADR:
€300
Room nights sold:
3,650
Rooms Revenue:
approximately €1.095 million.
Scenario 2 — Base Case
Occupancy:
60%
ADR:
€400
Room nights sold:
4,380
Rooms Revenue:
approximately €1.752 million.
Scenario 3 — High Performance
Occupancy:
70%
ADR:
€500
Room nights sold:
5,110
Rooms Revenue:
approximately €2.555 million.
The difference between these scenarios is substantial.
And it highlights the central point:
in a 20-key hotel, ADR and occupancy are not simply operating KPIs.
They are fundamental drivers of investment viability.
Every Point of Occupancy Matters
With 20 rooms:
1 percentage point of occupancy
represents approximately:
73 room nights per year.
At an ADR of €400:
73 × €400
=
approximately €29,200 of rooms revenue.
Ten percentage points of occupancy therefore represent approximately:
€292,000 of rooms revenue.
For an asset of this scale, the difference between 50% and 60% occupancy can materially change the economics of the entire project.
GOPPAR Will Be the Critical Operating KPI
ADR and RevPAR will not be enough.
The project will need to generate:
GOPPAR.
Gross Operating Profit per Available Room.
A five-star hotel generally carries higher costs across:
-
staffing;
-
guest services;
-
laundry;
-
housekeeping;
-
maintenance;
-
amenities;
-
F&B complexity;
-
marketing;
-
energy.
The question is therefore not simply:
how much revenue does each room generate?
It is:
how much operating profit does each available room generate?
The Restaurant Needs to Be a Demand Generator
The gastronomic component is one of the project's stated pillars.
The ambition to source almost entirely from the area between San Felice and Fondo reinforces:
-
identity;
-
storytelling;
-
local authenticity;
-
destination positioning.
But economically, the restaurant should be assessed across two separate dimensions:
Guest Service
and:
Independent Demand Generator.
If the restaurant relies only on the hotel's maximum 40 in-house guests, its scale will inevitably be limited.
If it attracts external customers, events and destination dining demand:
it becomes a second demand engine.
The correct equation is:
Hotel Guests
External Guests
Events
Experiences
=
F&B Revenue.
In a hotel with limited room inventory, non-room revenue can become critical.
The Five Hectares Also Need to Generate Economic Value
The agricultural land surrounding the property can support:
-
storytelling;
-
farm-to-table dining;
-
experiential tourism;
-
guest activities;
-
own production;
-
ESG positioning.
But the same principle applies:
storytelling and cash flow are not the same thing.
The land creates economic value if it improves at least one of the following:
-
ADR;
-
length of stay;
-
ancillary revenue;
-
demand;
-
guest loyalty;
-
brand equity.
Otherwise, it remains capital tied up in the project.
ESG Needs to Translate Into OPEX Efficiency or Pricing Power
The project includes a natural swimming pool, phytoremediation and water-reuse systems.
The economically relevant relationship should be:
Lower Environmental Impact
Lower Resource Consumption
Better Guest Perception
=
Lower OPEX + Higher Pricing Power.
When that happens, environmental sustainability and financial sustainability reinforce one another.
When it does not, ESG risks remaining simply:
additional CAPEX.
€500,000 per Key Is Not Yet the True Total Investment per Key
The theoretical ratio is useful.
But the definitive metric will be:
Total Investment per Key.
The complete equation should include:
Acquisition / Land
Construction
FF&E
OS&E
Professional Fees
Financing Costs
Pre-opening
Working Capital
Contingency
=
Total Capital Employed.
Only then will it be possible to establish the true amount of capital invested per unit.
From Total Capital Employed to Yield on Cost
Assume, purely for illustrative purposes, that final Total Capital Employed is:
€10 million.
To achieve a:
6% Yield on Cost
the project would need to generate:
€600,000.
At:
7%
€700,000.
At:
8%
€800,000.
These are not project targets.
They simply illustrate the amount of profit required to remunerate the capital employed.
If Total Capital Rises to €12 Million, the Threshold Changes Immediately
Suppose financing costs, pre-opening expenditure, contingency and other items push Total Capital Employed to:
€12 million.
An 8% Yield on Cost would then require:
€960,000 per year.
Almost:
€1 million of operating return from 20 units.
That is the real economic pressure behind low-density luxury hospitality.
The Critical Stress Test: ADR + Occupancy → EBITDA → Yield on Cost
We can take the analysis one step further using another purely methodological scenario.
Assume F&B, wellness and experiences add approximately 25% to rooms revenue, while the operation achieves different EBITDA margins.
Scenario A — Conservative
Rooms Revenue:
€1.095 million
Indicative Total Revenue:
approximately €1.37 million
Hypothetical EBITDA Margin:
20%
EBITDA:
approximately €274,000
On €10 million of capital:
Yield on Cost ≈ 2.7%.
Such a scenario would struggle to remunerate a capital-intensive development.
Scenario B — Base Case
Rooms Revenue:
€1.752 million
Indicative Total Revenue:
approximately €2.19 million
Hypothetical EBITDA Margin:
30%
EBITDA:
approximately €657,000
On €10 million of capital:
Yield on Cost ≈ 6.6%.
At this level, the economics begin to move closer to a return profile potentially consistent with a complex real estate-operating investment.
Scenario C — High Performance
Rooms Revenue:
€2.555 million
Indicative Total Revenue:
approximately €3.19 million
Hypothetical EBITDA Margin:
35%
EBITDA:
approximately €1.12 million
On €10 million of capital:
Yield on Cost ≈ 11.2%.
At this level, the economics of the investment change materially.
These figures are not forecasts.
They illustrate one fundamental point:
architectural quality does not determine returns.
Returns are driven by:
ADR + Occupancy + Non-Room Revenue + Margin.
Low Density Can Be an Advantage — But Only If It Creates Scarcity
Twenty units may appear limited.
In luxury hospitality, however, they can become:
Scarcity.
The virtuous sequence is:
Low Density
↓
Privacy
↓
Exclusivity
↓
Guest Preference
↓
ADR Premium
↓
Higher Value per Key.
If the premium does not materialise:
Low Density
simply becomes:
Low Inventory.
Economically, those are two very different outcomes.
The Real Competitive Set May Extend Well Beyond Val di Non
A project with approximately €500,000 of capital per unit should not necessarily be benchmarked only against nearby hotels.
Potential guests may also compare it with:
-
South Tyrol;
-
the Dolomites;
-
Lake Garda;
-
Austria;
-
Switzerland;
-
luxury rural resorts elsewhere in Italy.
The competitive set therefore becomes:
experiential.
Not simply:
geographical.
That increases the ambition of the project.
But also the pressure on product quality.
Destination Pull vs Property Pull
Demand can be generated in two different ways.
Destination Pull
The guest wants to visit Val di Non and then chooses the hotel.
Or:
Property Pull
The guest chooses Val di Non specifically because they want to stay at Maso Fandoveri.
For a high-capital, low-density project, the second dynamic becomes particularly important.
The property needs to aspire to become:
a Destination in Itself.
Year-Round Operation Requires Demand Creation
Operating throughout the year can improve:
-
capital utilisation;
-
staff stability;
-
revenue;
-
customer retention.
But it also creates:
-
year-round payroll;
-
utilities;
-
maintenance;
-
continuous marketing;
-
shoulder-season risk.
The real question is not:
can the property remain open all year?
It is:
can it generate profitable demand all year?
The distinction is fundamental.
November, March and Weekdays Will Be the Real Test
Summer and peak periods tell only part of the story.
Financial sustainability is tested when the destination generates less spontaneous demand.
That is when:
-
wellness;
-
destination dining;
-
retreats;
-
small corporate events;
-
private events;
-
experiential packages;
-
buyouts
need to generate incremental demand.
The business plan cannot be built only around peak season.
It must work through:
Shoulder-Season Economics.
Full Buyouts Can Turn Small Scale Into an Advantage
With 20 units, the entire property can potentially be sold as one exclusive product.
Weddings
Retreats
Corporate Boards
Private Celebrations
Brand Events.
A:
Full Property Buyout
can transform limited scale into:
Exclusivity.
And exclusivity can translate into pricing power.
Planning Risk Must Also Be Reflected in the Required Return
Municipal approval of the planning derogation is an important step.
But the authorisation process is not yet fully complete.
There is therefore still:
Planning Risk.
Planning risk can affect:
-
timing;
-
financing;
-
construction start;
-
inflation;
-
contractor pricing;
-
opening date.
And therefore expected returns.
Time Is Capital
Construction is indicatively expected to begin in May-June 2027.
Every month of delay can mean:
-
additional interest;
-
equity remaining tied up for longer;
-
construction-cost escalation;
-
lost revenue;
-
delayed EBITDA.
The relationship is straightforward:
Time = Capital.
Particularly in high-investment projects.
Cost ≠ Value
Once the project is completed, the market will not value Maso Fandoveri simply because €10 million was spent on it.
Value will depend on its ability to generate sustainable income.
The sequence becomes:
Revenue
↓
GOP
↓
EBITDA
↓
Sustainable Cash Flow
↓
Market Yield / Multiple
↓
Stabilised Value.
Spending €10 million does not automatically create an asset worth €10 million.
Still less an asset worth €15 million.
The Real Test: Stabilised Value vs Total Capital Employed
Again, purely as an illustration:
Total Capital Employed
€10 million.
If Stabilised Value were:
€11 million,
nominal value creation would be:
€1 million.
That may be insufficient to compensate for time and risk.
If Stabilised Value were instead:
€14 million,
the value-creation spread would become:
€4 million.
The difference is substantial.
The key metric therefore becomes:
Stabilised Value – Total Capital Employed.
But the Final Test Is Equity IRR
Even a positive value-creation spread is not enough.
The analysis must incorporate:
-
holding period;
-
leverage;
-
equity contribution;
-
cost of debt;
-
cash flow;
-
timing;
-
exit.
The framework must ultimately arrive at:
Equity IRR.
That is the metric that allows the Maso Fandoveri project to be compared with alternative investments.
Maso Fandoveri Is an Investment Case, Not Merely a Hotel Development
At first sight, the story is:
a new five-star hotel in Val di Non.
In reality, the project concentrates many of the defining variables of contemporary hospitality investment:
Heritage
Rural Luxury
Low Density
High Capital per Key
ESG
F&B
Experiential Hospitality
Year-Round Operation
Planning Risk
=
Complex Investment Case.
The Maso Fandoveri Investment Framework
The project can therefore be summarised as follows:
Historic Rural Asset
↓
Change of Use + Extension
↓
Planning Approval
↓
€10M Indicative Investment
↓
20 Units
↓
~€500k Theoretical Capital per Key
↓
Premium Product
↓
Premium ADR
↓
Occupancy
↓
GOPPAR
↓
EBITDA
↓
Yield on Cost
↓
Stabilised Value
↓
Equity IRR.
That is the real project.
Not simply developing a hotel.
But developing a hotel capable of:
remunerating the capital invested.
Conclusion: €500,000 per Key Is Not the Problem. What Those Keys Produce Is.
Maso Fandoveri contains many features that may support a strong high-end positioning:
-
nature;
-
heritage;
-
low density;
-
local gastronomy;
-
sustainability;
-
privacy;
-
experience.
But hotel investment is not remunerated by the quality of the concept.
It is remunerated by:
Cash Flow.
The right question is therefore not:
“Is €10 million too much for 20 units?”
It is:
“What ADR, GOPPAR and EBITDA must 20 units generate to remunerate €10 million of capital?”
And immediately after that:
“Is the market willing to pay enough to make that possible?”
If the answer is yes:
Low Density
Premium ADR
Strong GOP
can generate:
High Value per Key.
If the premium fails to materialise:
High Capital per Key
will simply translate into:
Low Return on Capital.
And that is precisely the line separating:
a beautiful hotel
from:
a good hotel investment.
InvestimentiAlberghieri.it | Hospitality Investment & Value Creation
The Maso Fandoveri case demonstrates why a luxury hospitality project should be assessed by integrating:
Acquisition + CAPEX + Capital per Key + ADR + Occupancy + GOPPAR + EBITDA + Yield on Cost + Stabilised Value + Equity IRR.
For analysis of hotel economics, positioning, governance and value: RobertoNecci.it.
For acquisitions, value creation, turnarounds, development and extraordinary hospitality transactions: Investhotel.it.
For business planning, organisation, revenue management and performance control: HotelManagementGroup.it.
For hotel investment analysis, business planning and hospitality asset value creation: