A commercially active hotel, 76 rooms identified in the court proceedings, a restaurant, conference facilities and a minimum bid of €862,500. At first glance, the numbers appear compelling. Yet the real investment case for the Europalace Hotel in Todi is not about price per key. It is about the separation between real estate, the hotel business, operations, FF&E, licences and the legal basis for occupation. That is where the true value — and the real risk — of the transaction lies.
In hospitality special situations, the entry price is often the most visible number.
It is not necessarily the most important one.
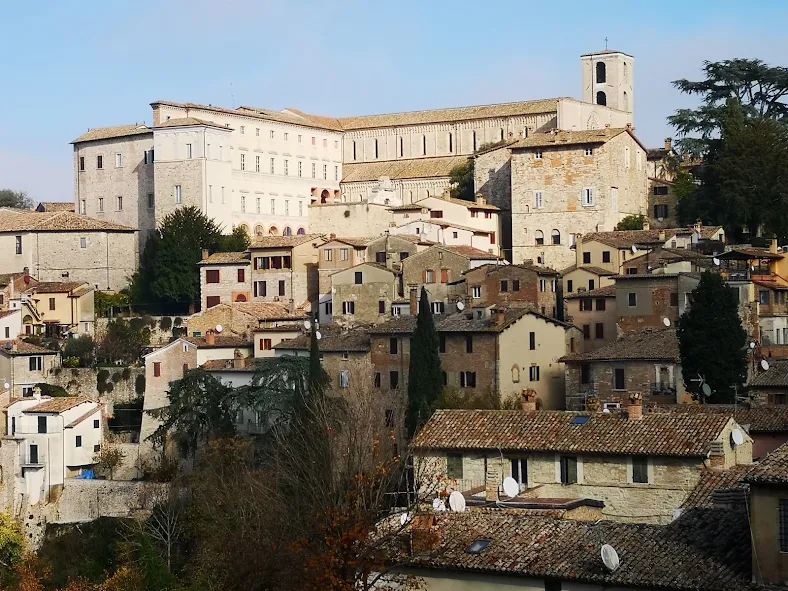
The Europalace Hotel in Todi, located in the Ponterio-Pian di Porto area, is a particularly clear example.
The property forms part of real estate enforcement proceeding no. 120/2022 before the Court of Spoleto, Lot 4.
The next sale is scheduled for 7 December 2026, with bids due by 4 December.
Deal Snapshot
| Item | Details |
|---|---|
| Proceeding | Real Estate Enforcement 120/2022 – Court of Spoleto |
| Lot | 4 |
| Sale date | 7 December 2026 |
| Base price | €1,150,000 |
| Minimum bid | €862,500 |
| Minimum bid increment | €16,000 |
| Rooms identified in the proceedings | 76 |
| Rooms marketed online | 72 |
| Implied minimum price per key | approx. €11,350 |
| Use | Hotel |
| Commercial status | Hotel currently marketed |
| Core issue | Separation between PropCo and OpCo |
According to the court documentation, the complex includes:
-
76 en-suite guestrooms;
-
reception;
-
offices;
-
bar;
-
breakfast room;
-
terrace;
-
restaurant;
-
conference room;
-
press room;
-
technical areas;
-
external courtyard;
-
two lifts;
-
internal vertical circulation.
The price is naturally the first figure to attract attention.
But this is precisely where a professional investor needs to avoid the first analytical shortcut.
€862,500 does not automatically mean acquiring an operating 76-room hotel at €11,350 per key.
Based on the publicly available information, it means being able to bid for the real estate included within the court-sale perimeter.
That distinction fundamentally changes the underwriting.
From €2.5 Million to €1.15 Million: The Repricing of the Real Estate
The sale history shows a progressive reduction in the asking base price.
| Sale date | Base price |
|---|---|
| 3 March 2025 | €2,500,000 |
| 23 June 2025 | €1,900,000 |
| 19 January 2026 | €1,600,000 |
| 27 July 2026 | €1,350,000 |
| 7 December 2026 | €1,150,000 |
Compared with the €2.5 million base price at the earliest identified sale attempt, the current figure represents a reduction of approximately 54%.
The repricing is therefore material.
But a lower price does not automatically mean greater value.
In distressed hospitality, it is essential to distinguish between:
Price Reduction
and
Value-Creation Potential
They are not the same thing.
The first is driven by the sale process.
The second depends on what the investor can actually acquire, control, finance, reposition and operate.
Real Estate and the Hotel Business Are Not the Same Asset
The most sensitive element of the Europalace case emerges from the occupancy status described in the documentation associated with the proceedings.
The property was occupied under a previous business-unit lease agreement that had expired.
The enforcement judge had authorised continued occupation until 30 June 2026, subject to a monthly payment of €2,500 plus VAT to the proceedings for the use of the real estate alone.
The available documentation expressly distinguished this arrangement from the hotel and restaurant business and the movable assets.
This separation is the core of the investment case.
Because it creates several distinct layers:
Real Estate
Hotel Business
FF&E
Operations
Licences
Contracts
Brand and Commercial Presence
Bookings and Customer Base
An investor acquiring the property should therefore not assume that everything currently enabling the hotel to appear and operate as a going concern automatically transfers with the real estate.
PropCo and OpCo: The Central Issue
In institutional hospitality, the distinction between PropCo and OpCo is fundamental.
The PropCo owns the real estate.
The OpCo operates the hotel business.
When the two sit within the same ownership perimeter, the analysis is relatively straightforward.
When they are separated through:
-
contracts;
-
business-unit leases;
-
enforcement proceedings;
-
management arrangements;
-
different ownership structures;
-
licences held by different entities;
the risk profile changes materially.
So does the potential for value creation, provided the different layers can be recombined effectively.
The Europalace Hotel in Todi appears to require precisely this type of analysis.
A prospective investor must therefore determine whether the ultimate transaction will involve:
-
acquiring the real estate with vacant possession;
-
acquiring the property while retaining the existing operator;
-
a PropCo investment supported by a new lease;
-
separate acquisitions of the property and hotel business;
-
a repositioning strategy involving a new operating model;
-
a subsequent integration of real estate ownership and hotel operations.
These scenarios have fundamentally different economic and financial implications.
Yet the Hotel Continues to Be Marketed
Alongside the real estate proceedings, Europalace maintains an active commercial presence.
The official website markets the property as a 4-star Superior hotel, offering:
-
guestrooms;
-
restaurant;
-
bar;
-
meeting facilities;
-
parking;
-
business and leisure accommodation.
The hotel is commercially presented with 72 rooms.
This creates an initial discrepancy that needs to be resolved:
76 rooms in the court documentation
versus
72 rooms in the commercial inventory
This is not necessarily a problem.
It may reflect:
-
out-of-order rooms;
-
different classifications of space;
-
units allocated to internal use;
-
a difference between the physical real estate configuration and the operating inventory.
But it is precisely the sort of issue that must be clarified before price per key can be used as a meaningful investment metric.
“New Owners”: Commercial Language Requires Caution
The hotel's website also refers to the Pastorelli family in connection with ownership and management since 2008.
Such commercial wording should not automatically be interpreted as evidence of current legal title to the real estate subject to the enforcement proceedings.
In hospitality, terms such as:
ownership
management
hotel
business
are frequently used in commercial communications with meanings that do not necessarily correspond to their precise legal definitions.
An investor therefore needs to establish, through documentary evidence:
-
who owns the real estate;
-
who owns the hotel business;
-
who operates the property;
-
who owns the FF&E;
-
who holds the operating licences;
-
who holds the CIN registration;
-
which entity employs the staff;
-
who controls bookings, contracts and commercial relationships;
-
under what legal basis the current operator occupies the property.
Only once these questions have been answered can an investor understand what is actually being acquired.
€11,350 per Key: Opportunity or False Signal?
The ratio is inevitably eye-catching.
€862,500 / 76 rooms = approximately €11,350 per key
But viewed in isolation, the figure may be highly misleading.
Price per key is useful only where the underlying transaction perimeter is genuinely comparable.
To have real analytical value, at least four variables must be understood:
Acquisition Perimeter
CAPEX
Operating Continuity
Stabilised EBITDA
Without these elements, price per key remains a preliminary indicator.
It is not an investment conclusion.
The Real Cost of the Transaction
The acquisition price is not the same as the capital required to execute the investment.
The appropriate framework is:
Acquisition Price + Transaction Costs + CAPEX + Working Capital + Repositioning Costs + Ramp-up = Total Investment Cost
Returns should then be measured against the Total Investment Cost.
An investor should therefore quantify at least:
-
deferred maintenance;
-
MEP upgrades;
-
fire-safety compliance;
-
energy-efficiency works;
-
guestroom refurbishment;
-
common-area renovation;
-
restaurant investment;
-
conference facilities;
-
FF&E;
-
hotel systems;
-
sales and marketing;
-
pre-opening or reopening costs;
-
working capital;
-
contingency.
An apparently inexpensive acquisition can quickly lose its appeal if CAPEX absorbs a significant share of the future enterprise value.
How Much Can Europalace Actually Generate?
The second layer of the analysis concerns the operating business.
A real estate enforcement process does not normally provide all the metrics required to underwrite a hotel.
At a minimum, an investor needs:
-
Occupancy;
-
ADR;
-
RevPAR;
-
rooms revenue;
-
F&B revenue;
-
meeting and events revenue;
-
ancillary revenue;
-
payroll;
-
energy costs;
-
OTA commissions;
-
maintenance expenditure;
-
GOP;
-
normalised EBITDA;
-
seasonality;
-
demand segmentation;
-
average length of stay.
Only once these figures have been reconstructed can an investor assess whether the hotel represents a genuine going concern capable of producing value independently of the underlying real estate.
Todi: The Positioning Should Not Be Viewed as Pure Leisure
The location of the Europalace deserves a specific reading.
The property is not located within Todi's historic centre. It occupies a more accessible position close to the E45.
That may constrain certain premium leisure segments.
But it may also broaden the potential demand mix.
The hotel could potentially capture:
-
leisure;
-
groups;
-
business travellers;
-
transit demand;
-
regional corporate accounts;
-
meetings;
-
events;
-
tour operators;
-
small conferences.
The meeting and conference facilities are therefore strategically relevant.
The appropriate question is not simply:
“How much tourism does Todi generate?”
It is:
“What demand mix can realistically support 72-76 rooms in this specific location?”
That is a much more useful underwriting question.
Potential Strategic Scenarios
Once ownership, operating arrangements and the current legal position have been clarified, a new investor could potentially consider several strategies.
Scenario 1 — Hold & Lease
Acquire the real estate and retain an operator under a sustainable lease agreement.
Key underwriting variables would include:
-
rent;
-
guarantees;
-
lease term;
-
tenant covenant strength;
-
FF&E obligations;
-
maintenance CAPEX.
Scenario 2 — Owner-Operator
Acquire the property and take direct control of the hotel business.
This would require:
-
acquiring or rebuilding the OpCo;
-
employees;
-
licences;
-
systems;
-
distribution;
-
working capital;
-
operating capabilities.
Scenario 3 — New Operator
Acquire the property and appoint a new hotel operator.
Potential structures could include:
-
lease;
-
hotel management agreement;
-
franchise;
-
white-label management.
Scenario 4 — Repositioning
Redesign the product around a positioning more closely aligned with local and regional demand.
Potential areas of focus could include:
-
guestrooms;
-
food and beverage;
-
MICE;
-
groups;
-
corporate business;
-
hybrid hospitality concepts.
Each scenario generates a different value proposition.
Investment Thesis
The investment thesis for the Europalace should not be built around a low acquisition price.
It should be built around the potential to recombine the real estate and operating business efficiently.
Potential strengths include:
-
76 rooms identified within the real estate perimeter;
-
base price reduced to €1.15 million;
-
minimum bid of €862,500;
-
significant repricing;
-
hotel still commercially present in the market;
-
restaurant;
-
meeting facilities;
-
parking;
-
accessibility;
-
ability to target multiple demand segments;
-
potential flexibility between PropCo, leasing and direct operations.
The real upside is therefore not simply acquiring “76 inexpensive rooms”.
It lies in the potential to create a more efficient property and operating structure than the one currently in place.
Key Risks
The principal risks requiring analysis include:
-
legal basis for occupation after 30 June 2026;
-
separation between real estate and operating business;
-
ownership of FF&E;
-
operating licences;
-
actual availability of the property;
-
discrepancy between physical rooms and marketed inventory;
-
CAPEX;
-
fire-safety and MEP compliance;
-
existing contractual arrangements;
-
employees;
-
ability of the current operation to generate sustainable EBITDA;
-
risk of overestimating ADR and occupancy;
-
possible need to replace the operator;
-
stabilisation period.
Next Catalyst
The next formal catalyst is the sale scheduled for 7 December 2026.
For a professional investor, however, the decisive work takes place before that date.
The following chain must be reconstructed:
PropCo → OpCo → Occupation Title → FF&E → Licences → Historical Trading → CAPEX → Stabilised EBITDA
Only once this sequence has been completed can a rational Maximum Bid Price be established.
Ten Questions That Must Be Answered Before Bidding
Before defining a maximum acquisition price, an investor should have documented answers to at least ten questions:
-
Who currently owns the real estate?
-
On what legal basis is the property currently occupied?
-
Who owns the hotel business?
-
Who owns the FF&E?
-
Who holds the operating licences and CIN registration?
-
Which entity employs the staff?
-
What is the five-year CAPEX requirement?
-
What are the normalised ADR, occupancy, RevPAR, GOP and EBITDA?
-
Which contractual structure maximises value?
-
What could the asset be worth once stabilised?
Only after addressing these questions can the analysis move from a real estate transaction to a true hospitality investment underwriting exercise.
The Value Is Not in the Price — It Is in Recombining the Pieces
The Europalace Hotel in Todi captures one of the most interesting dynamics in Italy's distressed hospitality market.
The real estate is subject to enforcement proceedings.
The hotel product continues to be commercially marketed.
The operating business and the property appear to follow different legal and economic perimeters.
That is where the real complexity lies.
And potentially, where the value lies too.
In hospitality, there is never only one layer of value.
There is:
Real Estate Value
Operating Business Value
Contract Value
Brand Value
Commercial Value
Replacement Cost
When these layers become separated, the investor's task is not simply to buy at a discount.
It is to recombine them into an economically sustainable structure.
That is the central issue in the Europalace investment case.
And it is also why the €862,500 minimum bid, despite being the most immediately visible figure, may ultimately be the least important number in the entire transaction.
Hospitality Ecosystem
RobertoNecci.it
Strategy, tourism economics, hospitality and market intelligence.
InvestimentiAlberghieri.it
Hotel assets, transactions, investments and hospitality special situations.
Investhotel.it
Hotel finance, capital structure, debt advisory, turnaround and value creation.
HotelManagementGroup.it
Hotel advisory, management and performance improvement.
Hotel Investment and Value-Creation Advisory
For preliminary investment analysis, operational due diligence, business planning, CAPEX assessment, repositioning studies and hospitality transaction structuring:
info@investimentialberghieri.it
Methodological Note
The information concerning pricing, property characteristics, the enforcement proceedings and the sale timetable is based on publicly available documentation relating to real estate enforcement proceeding no. 120/2022 before the Court of Spoleto.
Commercial information relating to the hotel's current market offering is derived from the property's public commercial presence and does not constitute evidence of ownership of the real estate, the current legal basis for occupation, ownership of the operating business or the transferability of licences, movable assets or contractual relationships.
This article does not constitute a property valuation or an investment recommendation.
Any transaction should be preceded by independent:
-
legal due diligence;
-
technical due diligence;
-
planning and zoning due diligence;
-
administrative due diligence;
-
tax due diligence;
-
financial due diligence;
-
operational due diligence.