The arrival of major international hotel groups in Umbria is not merely a tourism story.
It is a market signal.
When a global brand enters a destination, the perception of the asset changes, investor interest increases and the commercial potential of the hotel may improve significantly.
But there is a much more important question:
how much value does the arrival of an international hotel brand actually create for the owner?
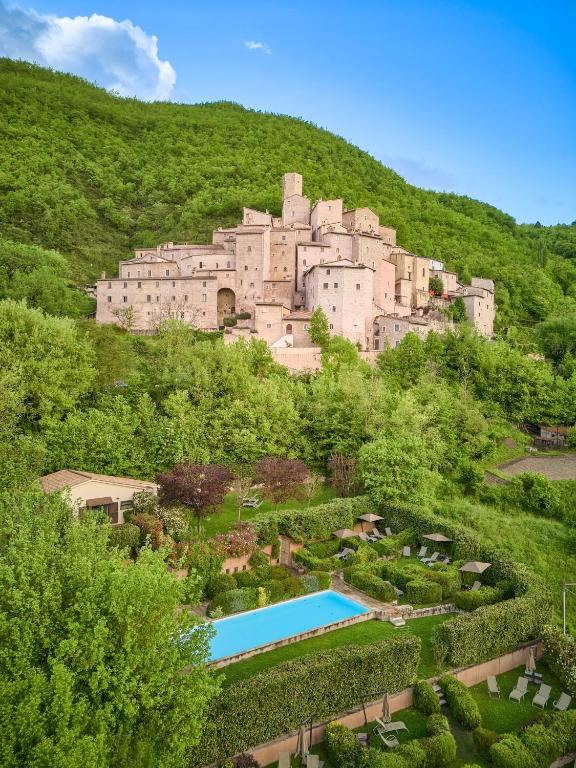
According to Passaggi Magazine, Hilton is reportedly interested in managing the hotels and restaurants within the Castello di Postignano complex in Valnerina, while in Assisi the Hotel Subasio is expected to join the Hilton network following a refurbishment programme.
These are two different transactions, yet both highlight a crucial issue for hotel investors:
brand prestige does not automatically translate into investment profitability.
For an investor, real value is created through the right balance between:
brand + contract + CAPEX + profitability + asset value.
And that balance must be assessed before any agreement is signed.
A brand can create value. But the numbers must prove it
An international hotel chain can deliver significant benefits:
-
stronger international visibility;
-
access to loyalty programmes;
-
global distribution;
-
greater commercial reach;
-
improved penetration of international source markets;
-
potential ADR growth;
-
stronger RevPAR;
-
higher market positioning;
-
greater asset recognition.
However, the brand also comes at a cost.
And that cost goes well beyond the contractual fee.
Investors must consider:
-
management fees;
-
franchise fees;
-
incentive fees;
-
reservation fees;
-
loyalty programme costs;
-
marketing contributions;
-
technology requirements;
-
audits;
-
training;
-
FF&E reserves;
-
brand-driven CAPEX;
-
renovation obligations;
-
contract duration.
This means the right question is not simply:
“How prestigious is the brand?”
The real question is:
“How much incremental profitability does the brand generate compared with the total cost of securing and maintaining it?”
Before signing, the investment needs to be independently assessed
When an owner is considering bringing in an international hotel group, the first step should be an independent assessment of the asset and the investment case.
At InvestimentiAlberghieri.it, this type of analysis starts with a fundamental question:
how much is the hotel worth today, and how much could it be worth after repositioning?
The assessment should include at least the following.
Current property value
What is the asset worth today in its present condition?
Value of the operating business
What is the economic value of the hotel business operating within the property?
Historical performance
Revenue, ADR, occupancy, RevPAR, GOP, EBITDA and cash flow should be reconstructed and normalised.
CAPEX requirements
What level of investment will be required to meet the brand’s standards?
Business plan
What level of operating performance can the hotel realistically achieve after repositioning?
Post-refurbishment value
What could the stabilised asset be worth once the project is completed?
Financial sustainability
Does the expected return justify the capital required?
This type of analysis allows the owner to negotiate from a much stronger position.
The 5 risks to assess before signing with a hotel brand
1. CAPEX is higher than expected
International brand standards can require significantly more investment than initially anticipated.
Every euro invested should be measured against the expected increase in profitability and asset value.
2. The contract is too long
A long-term management agreement may provide operational continuity, but it can also reduce the owner’s future flexibility.
Contract duration may also affect the future saleability of the property.
3. Fees absorb the GOP upside
Revenue growth does not necessarily mean stronger returns for the owner.
The key metric is the level of GOP remaining after all brand-related fees and charges.
4. Performance tests are too weak
If the agreement does not include measurable KPIs and effective termination mechanisms, the owner may remain locked into the contract even when performance is below expectations.
5. The value of the brand is assumed rather than proven
A brand may increase ADR and occupancy.
But the effect must be measured.
If the total cost of affiliation exceeds the resulting improvement in profitability, the economic value of the operation may actually decline.
Management agreements: the contract must protect the owner too
Management agreements are among the most common structures used between property owners and international hotel operators.
Under this model, the owner typically retains the economic risk of the hotel operation, while the operator receives remuneration for managing the property.
This makes a number of contractual provisions particularly important.
Management fee
How much is paid to the operator?
Incentive fee
Is variable remuneration genuinely linked to the creation of profitability?
Owner priority
How much income should the owner receive before incentive fees are applied?
Performance test
What performance thresholds must the operator achieve?
Termination clauses
Under what circumstances can the owner terminate the agreement?
FF&E reserve
How much capital must be set aside each year to maintain brand standards?
Approval rights
Which decisions remain under the owner’s control?
These provisions can materially alter the economics of the investment.
Franchising: the franchise fee is only part of the cost
A franchise model can offer greater operational autonomy than a management agreement, but it still carries a significant cost base.
Investors need to consider:
-
royalties;
-
reservation systems;
-
loyalty programmes;
-
marketing contributions;
-
IT systems;
-
training;
-
audits;
-
operating standards;
-
renovation requirements.
The correct financial analysis therefore compares:
incremental GOP generated by the brand
with
the total cost of affiliation.
It is this difference that determines the true economic value for the investor.
Legal protection and economic protection must work together
A common mistake is to separate legal review from financial analysis.
In reality, the two are closely connected.
A contractual clause can have a significant impact on:
-
cash flow;
-
profitability;
-
debt service capacity;
-
future saleability of the hotel;
-
property value;
-
enterprise value;
-
future operating flexibility.
This is why investor protection should involve both specialist legal advisers and advisers capable of assessing the economic impact of the contractual structure.
The strategic analysis developed through InvestHotel.it and RobertoNecci.it makes it possible to view the agreement not only as a legal document, but as a key determinant of investment value.
The Umbria case: the real signal is the interest of global operators
The potential arrival of Hilton in Umbria is important beyond the individual transactions involved.
It suggests that destinations previously regarded primarily as regional leisure markets are becoming increasingly attractive to international hotel operators.
This can result in:
-
increased investor interest;
-
stronger property values;
-
a higher volume of transactions;
-
repositioning towards the upper-upscale and luxury segments;
-
greater competition among operators;
-
new development opportunities.
However, one point should remain clear.
Market interest does not eliminate investment risk.
On the contrary, as markets become more attractive, asset selection becomes even more important.
The asset comes before the brand
Not every hotel can support an international repositioning strategy.
Investors need to assess:
-
location;
-
demand;
-
seasonality;
-
room count;
-
room size;
-
public areas;
-
planning use;
-
legal restrictions;
-
expansion potential;
-
accessibility;
-
refurbishment costs;
-
operating cost structure;
-
ability to generate GOP.
Only after this analysis does it make sense to determine which brand may be the best fit.
The correct process should therefore be:
asset analysis → business plan → CAPEX → operating model → operator selection → contract negotiation.
Not the other way around.
How much can the value of the hotel increase?
For an investor, the key issue is to understand how the value of the asset changes following repositioning.
Consider a purely illustrative example.
An independent hotel generates:
GOP: €800,000
Following the introduction of an international brand, GOP could rise to:
€1.4 million
At first sight, the value creation appears significant.
But before concluding that the transaction is attractive, the investor must deduct:
-
CAPEX;
-
cost of debt;
-
management fees;
-
incentive fees;
-
system charges;
-
loyalty costs;
-
marketing contributions;
-
FF&E reserves;
-
higher operating costs.
Only after these items are taken into account can we understand how much of the improvement actually remains with the owner.
The decisive question: what is the hotel worth before and after the brand?
Every transaction should be assessed under at least three scenarios.
Current scenario
What is the hotel worth today without any major intervention?
Independent repositioning scenario
What could the hotel be worth after refurbishment while remaining independently operated?
Branded scenario
What could the hotel be worth after repositioning under an international hotel brand?
This comparison shows whether the brand is genuinely creating incremental value.
It is particularly useful when an owner needs to choose between:
-
direct management;
-
management agreement;
-
franchise;
-
lease;
-
asset sale.
Owner-side advisory: why the analysis should be independent
When negotiating with an international hotel operator, the operator knows its own economic model extremely well.
The owner needs to understand its own model just as clearly.
For this reason, an independent adviser working exclusively on the owner’s or investor’s side can be highly valuable.
The adviser’s role is not to sell the hotel or broker the transaction.
It is to analyse:
-
the investment;
-
profitability;
-
value;
-
risk;
-
CAPEX;
-
operating structure;
-
scenarios;
-
economic sustainability of the proposed agreement.
InvestimentiAlberghieri.it operates precisely at this level of analysis.
An integrated ecosystem of expertise for hotel investments
Complex hotel transactions require a range of different skills.
Within the ecosystem, different components of the investment process are addressed through dedicated platforms.
InvestimentiAlberghieri.it focuses on hotel investments, valuations, transactions and value creation.
InvestHotel.it focuses on the economic and financial dynamics of hotel assets.
RobertoNecci.it provides analysis on hotel advisory, management, management control and hotel strategy.
Hotel Management Group focuses on hotel management and operational advisory.
Hotel Marketing Lab covers hotel marketing, revenue management, distribution, artificial intelligence and direct-booking growth.
Vertex Executive Search supports the search and selection of senior executives and management professionals in hospitality.
Roberto Necci Academy develops specialist training programmes for the hotel industry.
Investing in hotels means protecting capital before signing
The arrival of international hotel groups in Umbria is a positive signal for the market.
But for investors, the most important message is another one.
Value is not created by the logo on the façade.
It is created by structuring a transaction in which:
-
CAPEX is sustainable;
-
the contract is balanced;
-
the brand generates incremental profitability;
-
the financing structure is appropriate;
-
risk is controlled;
-
the final value of the asset increases.
That is the real meaning of investor protection in hotel investments.
Advisory services for hotel investors and owners
InvestimentiAlberghieri.it can support owners, investors, family offices and operators through:
-
preliminary investment analysis;
-
hotel valuation;
-
valuation of the hotel operating business;
-
business planning;
-
GOP and EBITDA analysis;
-
CAPEX analysis;
-
financial sustainability analysis;
-
assessment of post-refurbishment potential;
-
comparison between independent operation, franchising and management agreements;
-
economic analysis of operator proposals;
-
owner-side advisory support during negotiations;
-
assessment of potential future asset value;
-
economic and strategic support alongside legal due diligence.
Are you considering the acquisition, refurbishment, affiliation or repositioning of a hotel?
Before signing with an operator, an international hotel group or a lender, it is possible to carry out an independent assessment of the investment, the value of the asset and the economic sustainability of the transaction.
For advisory enquiries: info@investimentialberghieri.it
Source: Passaggi Magazine – “Le major Usa del turismo sbarcano in Umbria: Hilton in Valnerina e ad Assisi”. Information concerning negotiations, parties involved and the development status of the properties mentioned is based on the cited journalistic source and should be understood according to the status of the transactions reported at the time of publication.