The decline in traditional hotel supply raises a fundamental question for owners and investors: is it more profitable to sell, convert or reposition a hotel through a more efficient operating model? An in-depth financial and strategic analysis of hospitality investment opportunities in one of Italy's most prestigious coastal destinations.
21 November 2026 | InvestimentiAlberghieri.it — Hospitality Investment & Asset Advisory
Versilia Is Losing Hotels, but the Destination's Tourism Appeal Remains Strong
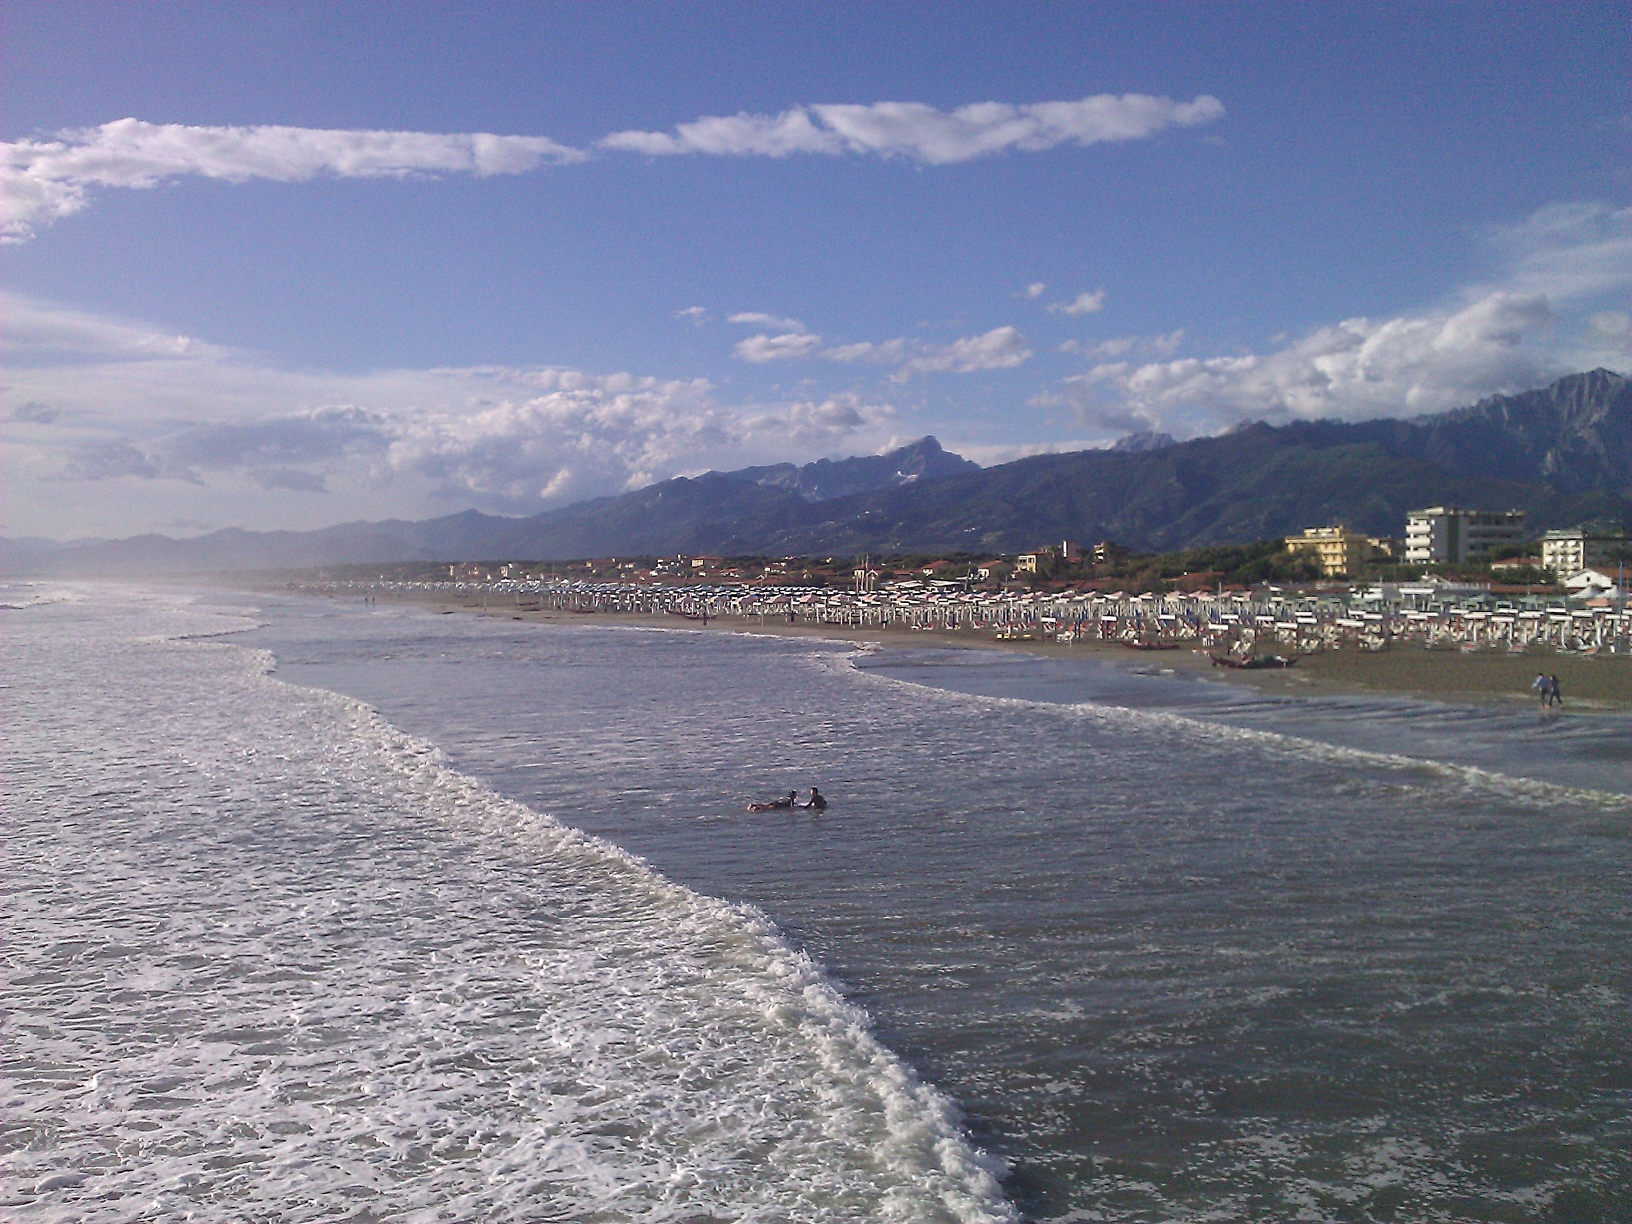
Versilia remains one of Italy's most established and prestigious tourism destinations. Forte dei Marmi, Viareggio, Pietrasanta and Camaiore continue to benefit from strong destination recognition, prime real estate locations and a well-established ability to attract both domestic and international visitors.
Yet beneath this competitive positioning, the region's hospitality sector is undergoing a significant structural transformation.
According to Confcommercio figures reported by the local press on 18 and 20 November 2026, Versilia recorded a net decline of 27 hotels and 1,007 hotel beds between 2014 and 2025.
Over the same period, the number of non-hotel accommodation establishments increased substantially, reflecting the growing importance of alternative hospitality formats.
This does not necessarily indicate a crisis in the destination itself. Rather, it suggests that part of Versilia's traditional hotel sector is finding it increasingly difficult to maintain the operating efficiency, investment capacity and competitive positioning required by today's hospitality market.
However, the real issue extends beyond the number of hotels disappearing from official statistics.
The fundamental question is how much real estate and business value is lost when a hotel can no longer operate as an economically sustainable enterprise.
For hotel owners, investors and operators, the answer should not automatically be to sell the property or pursue a change of use.
Before taking either route, it is essential to establish whether profitability could be restored through commercial repositioning, a more effective operating model or a financially sustainable refurbishment programme.
This principle underpins the investment analysis and hotel asset valuation activities of InvestimentiAlberghieri.it.
It also explains why Roberto Necci's tailored hotel advisory approach is particularly relevant to independent hotel owners seeking to improve profitability without surrendering ownership, brand identity or strategic control.
The Numbers: Fewer Hotels, More Alternative Accommodation
The figures reported by Confcommercio provide a clearer picture of the transformation taking place across Versilia's accommodation market.
| Indicator | 2014 | 2025 | Change |
|---|---|---|---|
| Hotel establishments | 331 | 304 | -27 |
| Hotel bed capacity | 18,827 | 17,820 | -1,007 |
| Non-hotel accommodation establishments | 221 | 375 | +154 |
| Total accommodation bed capacity | 34,574 | 32,819 | -1,755 |
Source: Confcommercio data reported by Il Tirreno, November 2026.
The number of hotels declined by approximately 8.2%, while non-hotel accommodation establishments increased by approximately 69.7%.
The reduction of 27 hotels represents the net change in the number of registered establishments. It should not be interpreted as evidence that exactly 27 individual hotels closed permanently during the period.
The figures point towards an increasingly differentiated hospitality market, with higher-quality hotel products competing alongside alternative accommodation formats.
Several factors may explain the changes: insufficient operating scale, capital expenditure requirements that cannot be justified by projected returns, outdated facilities, succession issues, changes in consumer behaviour and alternative real estate strategies.
Some properties may have lost their competitive position not because the destination lacks demand, but because their owners have been unable to convert that demand into adequate financial performance.
This distinction matters.
A hotel in a prestigious location is not automatically a profitable hospitality investment.
Its ability to create value depends on the relationship between achievable revenue, operating costs, required capital expenditure, property-specific constraints and the cost of capital.
Forte dei Marmi: Can Hotel Redevelopment Reverse the Trend?
Information published on 20 November highlights signs of renewed investment and hotel redevelopment in parts of Versilia.
In Forte dei Marmi, the municipal administration has outlined an urban planning approach designed to limit additional land consumption while allowing existing hotels to upgrade their facilities and introduce new services.
Projects mentioned in the local press include the redevelopment of the former Hotel Paradiso al Mare, refurbishment initiatives involving the Alcione and Mirabeau hotels, the reopening of Hotel America and restoration works at the former Hotel Franceschi.
These projects are at different stages of implementation and should not be interpreted as components of a single real estate transaction.
Deputy Mayor Andrea Mazzoni also reported that, during the first seven months of 2026, hotels in Forte dei Marmi recorded a 7.8% increase in arrivals and a 3.1% rise in overnight stays compared with the corresponding period in the previous year.
These figures, reported by the press on the basis of statements from the local administration, suggest that demand for hotel accommodation may remain resilient.
They do not, however, establish that every hotel can achieve satisfactory returns.
The redevelopment of existing hotel stock must therefore begin with the economic sustainability of the operating business, rather than the prestige of its real estate location alone.
Why Hotels Can Underperform Even in Prime Destinations
A hotel can operate in a market characterised by high room rates and still deliver disappointing financial results.
Common causes include pronounced seasonality, insufficient operating scale, high fixed costs, outdated commercial positioning and inefficient distribution strategies.
These challenges are often compounded by inadequate management reporting and financial controls.
An owner may know the hotel's annual turnover without having a sufficiently detailed understanding of the actual contribution generated by rooms, food and beverage, ancillary services and individual operating departments.
In other cases, the problem lies in the capital structure: the investment required to refurbish the property may exceed the economic value that the business can reasonably generate.
These situations call for different solutions.
A hotel offering an attractive product but suffering from operational inefficiencies may have substantial scope for improvement without any need to change its use.
A severely outdated property, by contrast, may require comprehensive redevelopment or an alternative real estate strategy.
The decision should be supported by a professional assessment capable of distinguishing the value of the hotel operation from the value of the underlying real estate.
How Much Could a Refurbished Hotel in Versilia Generate? Three Financial Scenarios
To illustrate the financial impact of different management strategies, consider a hypothetical 40-room independent hotel operating primarily on a seasonal basis.
The model compares three alternatives.
Scenario A — Existing Operations: The hotel continues to operate with its current product, organisational structure and commercial positioning.
Scenario B — Refurbishment and Professional Management: The property is upgraded and the business adopts more efficient operating procedures, supporting improved room rates and a longer operating season.
Scenario C — Premium Repositioning: Refurbishment is combined with a higher-end market position, an enhanced service offering and further seasonal extension.
Revenue and Operating Profitability Simulation
| Indicator | A: Existing | B: Refurbished | C: Premium |
|---|---|---|---|
| Rooms | 40 | 40 | 40 |
| Operating days per year | 180 | 220 | 240 |
| Occupancy | 70% | 72% | 75% |
| Average Daily Rate (ADR) | €200 | €220 | €235 |
| Room revenue | €1,008,000 | €1,393,920 | €1,692,000 |
| Ancillary revenue | €120,960 | €209,088 | €304,560 |
| Total revenue | €1,128,960 | €1,603,008 | €1,996,560 |
| GOP margin | 23% | 29% | 32% |
| Gross Operating Profit (GOP) | €259,661 | €464,872 | €638,899 |
Illustrative financial model only. These figures are not verified Versilia market benchmarks, an independently validated business plan or forecasts for any specific property. Ancillary revenue is assumed to equal 12%, 15% and 18% of room revenue, respectively.
The differences are substantial.
Under Scenario B, annual GOP increases by approximately €205,000 compared with existing operations.
Under Scenario C, the improvement reaches approximately €379,000 per year.
These results reflect the combined effects of operating season, occupancy, average room rate, ancillary revenue and operating margin. None of these improvements should be assumed achievable without validating market demand and operational capabilities.
Gross Operating Profit is not equivalent to normalised EBITDA, free cash flow or the income attributable to the real estate owner.
A proper investment assessment must also account for costs below GOP, potential management fees, major maintenance, furniture, fixtures and equipment replacement reserves, working capital requirements, taxation and debt service.
How Much Capital Would Be Required?
The analysis can be extended by introducing additional hypothetical investment assumptions.
| Indicator | B: Refurbished | C: Premium |
|---|---|---|
| Assumed initial CAPEX | €1,600,000 | €2,200,000 |
| Incremental annual GOP | €205,211 | €379,238 |
| Assumed incremental annual cash flow* | €130,000 | €220,000 |
| Simple incremental return on CAPEX | 8.1% | 10.0% |
| Simple payback period | 12.3 years | 10.0 years |
The incremental cash flow figures are separate screening assumptions, intended to reflect relevant recurring operating costs and cash outflows associated with the investment, before financing and taxation. They cannot be derived directly from GOP. The model excludes the acquisition price, potential business interruption during refurbishment and any terminal value.
These calculations do not represent an Internal Rate of Return (IRR) and are insufficient to establish whether either investment is economically attractive.
A professional feasibility assessment would require a multi-year financial model incorporating discounted cash flows, demand scenarios, CAPEX sensitivities, an appropriate discount rate and exit assumptions.
The simulation illustrates a fundamental principle:
Hotel refurbishment creates value only when the expected improvement in financial performance adequately compensates for the capital invested and the risks undertaken.
Upgrading guestrooms is not enough. The investment must be supported by a credible, sustainable increase in operating performance.
From Operating Profit to Real Estate Value: What Is a Hotel Really Worth?
Hotel valuation cannot be reduced to applying a generic revenue multiple.
At least three distinct components must be considered.
Real Estate Value: The value of the physical property and associated rights, taking account of location, condition, permitted use, income attributable to the property and legally available alternatives.
Hotel Business Value: The value of the operating business, including transferable goodwill, organisational capabilities and its ability to generate future economic benefits.
Total Investment Value: The return achievable on the capital committed to acquisition, refurbishment and operation, taking account of risk and projected cash flows.
This distinction becomes particularly important when ownership of the property is separated from the hotel operating company.
Illustrative Real Estate Valuation Sensitivity
For methodological purposes, assume that a hotel can generate €250,000 of annual normalised net income attributable to the real estate, after the costs properly borne by the property owner.
Applying alternative hypothetical capitalisation rates produces the following results.
| Capitalisation rate | Illustrative capital value |
|---|---|
| 7.0% | €3,571,429 |
| 8.0% | €3,125,000 |
| 9.0% | €2,777,778 |
These capitalisation rates are not verified market yields for Versilia. The assumed €250,000 net property income is independent of the earlier GOP scenarios.
The purpose is simply to demonstrate how materially the capital value of a hotel property can change depending on its sustainable income and the yield required by investors.
In practice, valuation methodologies must be consistent with the contractual structure, operating risk, comparable transactions and quality of projected cash flows.
An owner's asking price, the property's historical acquisition cost and the amount invested over time are not necessarily reliable indicators of its current economic value.
Condohotels in Tuscany: An Attractive Opportunity, but Not for Every Property
The condohotel model is increasingly discussed as a potential strategy for redeveloping existing hotel assets.
Subject to applicable legal requirements, the model combines hotel accommodation with residential units within an integrated property and operating structure.
Article 25 of Tuscany Regional Law No. 61/2024 establishes a 40% limit for residential units, calculated with reference to the total surface area of the relevant property complex.
Italy's national framework, established by Presidential Decree of the Council of Ministers No. 13/2018, also imposes specific requirements.
These include a 40% limit calculated on the net floor area allocated to guestrooms, a minimum of seven remaining hotel rooms, a hotel classification of at least three stars following refurbishment and unified management for the legally prescribed period.
The national and regional provisions use different measurement bases and must therefore be considered together, alongside the applicable municipal planning regulations.
The 40% threshold does not create an automatic right to convert part of any hotel into private residential apartments.
For investors, one potential advantage is the ability to generate proceeds from residential unit sales to help finance the refurbishment of the hotel component.
However, the model also carries risks.
Reducing the floor area dedicated to hospitality can limit the hotel's future revenue-generating capacity. Residential sales may provide immediate liquidity without necessarily improving the long-term profitability of the remaining hotel business.
Investors must also consider construction costs, marketing expenses, planning approvals, tax implications, financing requirements and the obligations associated with unified management.
A robust feasibility assessment should therefore evaluate the economics of the residential development and the remaining hotel operation separately.
A condohotel should be viewed as a sustainable investment structure, not simply as a mechanism for introducing residential development into a former hotel property.
Sell, Lease, Enter a Management Agreement or Continue Operating? Which Strategy Creates the Most Value?
For hotel owners, the strategic decision should not begin with a search for a buyer.
It should begin with a comparison of the potential economic outcomes available under different business and ownership structures.
| Strategy | Potential advantage | Principal risk |
|---|---|---|
| Restructured owner-operated model | Retaining control while improving profitability | Insufficient management capabilities |
| Hotel business lease | Potentially more predictable contractual income for the lessor | Operator default or financial weakness |
| Hotel management agreement | Access to professional expertise and operating systems | Management fees and continued exposure to business risk |
| Premium refurbishment | Improved positioning and pricing potential | CAPEX overruns and weaker-than-expected demand |
| Condohotel conversion | Monetisation of a residential component | Regulatory constraints and reduced hotel capacity |
| Asset disposal | Immediate liquidity and transfer of investment risk | Loss of potential future appreciation |
The most appropriate option must be supported by a comparative business plan.
In particular, income received under a hotel business lease, hotel operating profit and net income attributable to the real estate owner are not interchangeable financial measures.
They represent different economic interests, risk allocations and contractual responsibilities.
This is precisely where professional hospitality advisory can help owners avoid potentially irreversible decisions.
The investment analysis activities of Investhotel.it focus on assessing opportunities to acquire, reposition and enhance hospitality assets, with particular attention to financial sustainability and the relationship between real estate capital and hotel operations.
Professional Hotel Advisory: An Alternative to Selling or Converting the Property
One of the most frequently overlooked aspects of hotel ownership is the distinction between an underperforming asset and an underperforming operation.
An owner may consider selling because the hotel's current profitability appears inadequate.
However, that decision is sometimes taken without first establishing whether the problem is structural or managerial.
The difference is critical.
A structural problem may require a fundamental reassessment of the property, its economic function or its permitted use.
A managerial problem may be addressed through better systems, commercial strategy, financial controls and organisational efficiency.
Professional hotel management can influence revenue management, distribution, cost control, staffing, financial planning, service quality and operating margins.
These capabilities are commonly associated with major international hotel groups, but they can also be introduced into independently owned properties.
The Efficiency of International Hotel Chains Without Sacrificing Your Hotel's Identity
Independent hotel owners do not necessarily have to choose between traditional management practices and joining a major international hotel chain.
A third option is available: a structured management advisory programme designed to introduce professional operating standards while preserving the hotel's distinctive identity, brand and ownership structure.
Roberto Necci explores this approach in detail in:
TAILORED HOTEL ADVISORY: THE EFFICIENCY OF MAJOR HOTEL CHAINS WITHOUT LOSING YOUR HOTEL'S INDIVIDUAL IDENTITY
This approach is particularly relevant to owners seeking stronger operating performance, investors assessing potential acquisitions and real estate companies looking to understand the commercial potential of their hospitality portfolios.
The objective is to identify which initiatives can genuinely improve business performance before committing capital to refurbishment, disposal or conversion.
Hospitality advisory does not replace the legal, tax, technical or planning assessments undertaken by the relevant specialists. Rather, it brings these considerations together within an integrated economic and strategic framework.
Why a Preliminary Hotel Assessment Matters Before Investing
A meaningful hotel asset assessment should answer five fundamental questions.
1. What is the hotel worth today?
The analysis must distinguish the underlying real estate value, any separately identifiable business value and the liabilities or contractual obligations affecting the transaction.
2. How much could the hotel generate under a different operating model?
Answering this question requires a revenue and cost model supported by historical operating data, relevant benchmarks and transparent assumptions.
3. How much capital is genuinely required?
CAPEX estimates must include construction, mechanical and electrical systems, furniture and equipment, professional fees, implementation timelines, contingencies and potential business interruption.
4. Which management structure offers the best economic outcome?
Owner operation, business leasing, management agreements and hybrid structures create different financial, operational and contractual risk profiles.
5. Which alternative generates the highest risk-adjusted value?
The assessment should consider financial scenarios, debt service capacity, discounted cash flows and returns on invested capital.
Without this analysis, a hospitality investment can become an inefficient allocation of capital.
Conversely, a properly structured project may significantly improve the value of an existing hotel without requiring a change of use.
Versilia's Next Investment Cycle: From Property Ownership to Professional Asset Management
The net reduction of 27 hotels since 2014 should not be viewed solely as a decline in accommodation supply.
It is a signal of structural market change.
Guest expectations are evolving, quality requirements are increasing, operating and investment costs demand greater discipline, and capital providers are becoming more selective.
For independent hotels, the challenge is to transform properties that often benefit from excellent locations into financially sustainable businesses.
There is no universal solution.
Some hotels may benefit from refurbishment. Others could achieve better results through professional management partnerships, while certain properties may be more suitable for mixed-use redevelopment or strategic disposal.
Every decision, however, should begin with one principle:
A hotel's value is determined not only by its location, but by the scale, quality and sustainability of the economic cash flows it can generate.
Versilia has the potential to become a significant market for a new cycle of hospitality investment and repositioning.
The genuine opportunity lies in identifying assets for which a credible operating strategy, sound financial structure and sustainable long-term investment case can be developed.
Do You Own a Hotel in Versilia? Before Selling or Converting It, Discover What It Could Really Be Worth
A hotel that underperforms is not necessarily a hotel that should be sold.
It may be a business that needs a different management model, stronger commercial positioning or a more effective financial and operational structure.
Through Roberto Necci's professional advisory expertise, InvestimentiAlberghieri.it supports confidential preliminary assessments for:
-
Hotel owners experiencing disappointing profitability.
-
Independent operators considering refurbishment or disposal.
-
Investors evaluating hotel acquisition opportunities.
-
Real estate companies holding hospitality assets.
-
Operators considering hotel management agreements or business leases.
Advisory assignments may include financial assessment, hotel and real estate valuation, feasibility studies, CAPEX analysis, operating model comparisons and strategic asset repositioning.
Before Making a Major Real Estate Decision, Understand Your Hotel's True Economic Potential.
Discover how to introduce the efficiency of international hotel chains into an independently owned hotel:
EXPLORE ROBERTO NECCI'S TAILORED HOTEL ADVISORY APPROACH
For a confidential initial discussion about your property and potential advisory requirements:
Contact: info@investimentialberghieri.it
When enquiring, please include the hotel's location, approximate room count, property type and the principal issue or investment decision you would like to assess.
Professional Resources
InvestimentiAlberghieri.it — Hotel investment analysis, feasibility studies and hospitality real estate advisory.
RobertoNecci.it — Strategic hotel advisory, operational management and business performance improvement.
Investhotel.it — Hospitality investment opportunities, hotel asset analysis and value-enhancement strategies.
Sources and Methodological Notes
-
Il Tirreno, 18 November 2026 — “Persi mille posti letto e 27 hotel in Versilia, cresce invece l'offerta extra alberghiera.” Original Italian source.
-
Il Tirreno, 20 November 2026 — “Turismo in Versilia, 27 alberghi chiusi in dieci anni? Qualcosa sta cambiando.” Original Italian source.
-
Tuscany Regional Law No. 61 of 31 December 2024, Article 25 — Condohotel regulations.
-
Italian Prime Ministerial Decree No. 13 of 22 January 2018 — National regulatory framework governing condohotels.
Methodological Disclaimer
The regional market figures are drawn from the cited news sources reporting Confcommercio data. The financial simulations are original illustrative assumptions and do not constitute certified valuations, investment recommendations or forecasts for any identifiable property. The CAPEX assumptions, ADR, occupancy levels, operating margins, capitalisation rates and investment returns should not be interpreted as verified Versilia market benchmarks. Any actual transaction or investment decision requires property-specific financial, commercial, technical and legal due diligence.